10 Tech-Smart Money Rules Frugal People Follow to Stay Financially Free.Two years ago, I sat down at my desk on a rainy Sunday morning in Austin to audit my bank accounts. I expected the usual culprits: grocery bills, rent, maybe an overpriced dinner or two. What I actually found shook me. Hidden between routine transactions was a slow, silent bleed of $384 a month in subscriptions I barely touched. Cloud storage tiers I didn’t need, an old gym membership running on autopay, an IDE plugin subscription I forgot existed, and four video streaming packages running concurrently.
- 1. 1. Deploy FinTech Automation Before Lifestyle Creep Bites
- 2. 2. Track Spending with Zero-Based Budgeting (and Skip Passive Aggregators)
- 3. 3. Run a Quarterly Sweep to Crush SaaS Subscription Creep
- 4. 4. Run Hardware Decisions Through the Cost-Per-Use Metric
- 5. 5. Beat Planned Obsolescence by Championing the Right to Repair
- 6. 6. Embrace Open-Source Software Over Costly Commercial Licenses
- 7. 7. Combine Micro-Investing with Low-Cost Index Funds
- 8. 8. Maintain a Sensible Digital Asset Allocation (and Avoid the Speculative Hype)
- 9. 9. Introduce a Mandatory 72-Hour Digital Friction Buffer
- 10. 10. Anchor Daily Decisions to the FIRE Movement Mindset
- 11. Expert Insight: The “One-In, One-Out” Tech Rule
- 12. Frequently Asked Questions
- 13. Isn’t tracking every dollar exhausting over the long term?
- 14. How much should I actually keep in a High-Yield Savings Account?
- 15. Does buying refurbished hardware really save money, or is it risky?
- 16. What is the quickest way to tackle SaaS subscription creep?
- 17. Can micro-investing replace an employer-sponsored retirement account?
Living in tech circles, we talk endlessly about efficiency, optimization, and automation in code. Yet, when it comes to our personal finances, many of us let friction-free spending hollow out our wealth.
True frugality isn’t about skipping a three-dollar coffee or surviving on instant ramen. It’s about building intentional systems that eliminate waste so your money can buy what actually matters: your autonomy. Frugal people who reach long-term independence don’t rely on brute willpower. They follow clear, repeatable operating principles.
Here are the 10 tech-smart rules that keep everyday frugal people financially secure and genuinely free.

1. Deploy FinTech Automation Before Lifestyle Creep Bites
When cash sits in a primary checking account, our brains treat it as disposable. Behavioral economists call this the “availability bias,” but in daily life, it just means you buy things you don’t need simply because the balance looks healthy.
Frugal people bypass human temptation entirely using FinTech automation. The day their direct deposit clears, an automated split routes money across accounts before they can ever spend it:
- First Split: Fixed living expenses stay in a checking hub.
- Second Split: Emergency funds head directly into a High-Yield Savings Account (HYSA) yielding 4% to 5% APY (platforms like Ally, Marcus, or Wealthfront work well here).
- Third Split: Long-term investments flow immediately into tax-advantaged accounts (Roth IRA, 401(k), or regional equivalents like an ISA or TFSA).
By the time you look at your mobile banking app, the only balance visible is what you’re genuinely allowed to spend on groceries and guilt-free leisure. You treat savings as an unnegotiable recurring bill.
💰 More Cheap Living Tips You'll Love
- Debt Snowball on a Low Income: Does It Still Work in 2026-27?
- Debt Snowball Method: How It Works (With Real Example)
- Debt Avalanche Method Step by Step: Fast Debt Payoff
- How Long to Pay Off Debt? Tech Tools to Find Out Fast
- Debt Snowball Worksheet: How to Fill It Out Correctly
- First Steps to Take When You Decide to Get Out of Debt
2. Track Spending with Zero-Based Budgeting (and Skip Passive Aggregators)
For years, people recommended passive account linkers like the old Mint app. You linked your cards, forgot about it for 30 days, and then received a colorful bar graph showing you had overspent on burritos again. Passive tracking does not change behavior; active friction does.

Frugal minds lean into zero-based budgeting. In this framework, every single dollar that enters your possession gets assigned a specific job before the month starts: $1,200 for rent, $400 for groceries, $150 for utilities, $300 for an index fund, and $50 for pocket cash. If unexpected costs crop up, you physically reallocate money from another category to cover it.
Tools like YNAB (You Need A Budget) or open-source alternatives like Actual Budget force this friction. When you have to actively reconcile your accounts, you develop an intuitive, visceral awareness of what things cost.
3. Run a Quarterly Sweep to Crush SaaS Subscription Creep
Software-as-a-Service companies design their billing engines around human forgetfulness. They offer a 14-day free trial, ask for credit card details, and gamble on the fact that you will forget to cancel. This is SaaS subscription creep, and it quietly erodes disposable income across millions of households.
Every quarter, pull your PDF statements or use a dedicated tracking tool like Bobby or an offline spreadsheet. Audit every recurring line item using three questions:
- Have I used this service in the last 14 days?
- Does a free, self-hosted, or native alternative exist?
- Would I re-buy this today at full price?
If the answer is no, kill it immediately. If you need it again three months down the line, resubscribing takes ten seconds. Treating digital tools as transient rentals rather than permanent monthly commitments easily saves hundreds of dollars every quarter.
4. Run Hardware Decisions Through the Cost-Per-Use Metric
Cheap products are often deceptively expensive. Buying a sub-$200 laptop that slows down after six months, shatters its plastic hinge, and needs replacement within a year is a terrible deal compared to buying a durable, refurbished machine that lasts six years.
Financially savvy buyers run hardware decisions through the Cost-per-use metric (CPUM):
$$\text{Cost Per Use} = \frac{\text{Total Purchase Price} + \text{Maintenance Costs}}{\text{Total Days or Hours Used}}$$
Let’s look at a practical hardware comparison:
| Device Choice | Upfront Cost | Lifespan | Estimated Uses | Effective Cost-Per-Use | | :— | :— | :— | :— | :— | | Ultra-budget disposable tablet | $180 | 1 year (slows down, broken screen) | 200 sessions | $0.90 / use | | Refurbished enterprise laptop (ThinkPad/MacBook) | $650 | 5 years (upgradable, durable) | 1,500 days | $0.43 / use | | Fast-fashion wired mouse | $15 | 4 months (switch fails) | 90 days | $0.16 / day | | High-grade ergonomic mouse | $80 | 6 years (repairable switches) | 1,800 days | $0.04 / day |
Frugal people don’t chase the lowest sticker price; they chase the lowest lifetime ownership cost.
5. Beat Planned Obsolescence by Championing the Right to Repair
Tech manufacturers love lock-in ecosystems. They solder RAM directly to motherboards, glue phone batteries behind proprietary screws, and push software updates that choke older chipsets. This deliberate design cycle—planned obsolescence—forces consumer upgrades before hardware actually dies.
Those who stay financially free resist the cycle by embracing the Right to Repair.
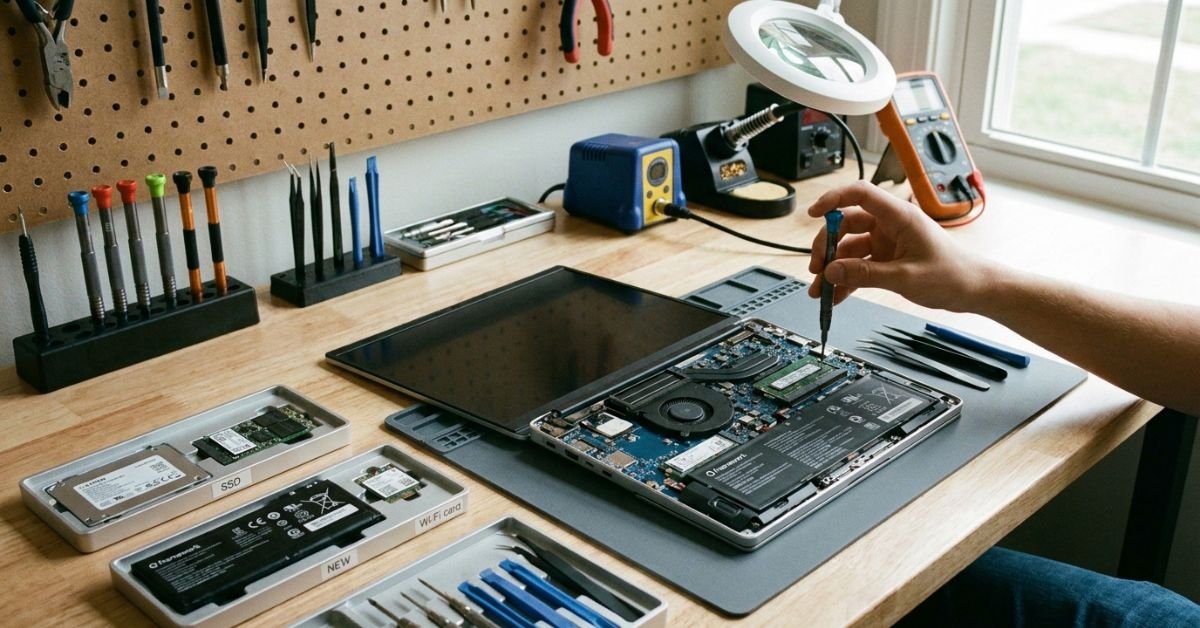
Instead of trading in an iPhone or Pixel the second its battery health hits 79%, grab an affordable repair kit from iFixit or a trusted local shop. Swapping an internal lithium-ion battery costs roughly $30 to $60 and takes an hour of careful work; buying a new flagship phone costs $1,000+. When buying laptops, look into repair-friendly modular machines like the Framework Laptop, or buy off-lease business enterprise units (like Lenovo ThinkPads or Dell Latitudes) whose parts are cheap, abundant, and easily swappable.
6. Embrace Open-Source Software Over Costly Commercial Licenses
Why pay monthly licensing fees for closed software ecosystems when exceptional open alternatives are maintained by global developer communities?
Frugal tech users routinely replace bloated paid services with lean, privacy-respecting open-source software:
- Ditch Microsoft 365 or Google Workspace extras for LibreOffice or locally run documents.
- Swap Adobe Photoshop subscription fees for GIMP, Krita, or vector tools like Inkscape.
- Replace subscription cloud notes (like Notion or Evernote) with Obsidian or Logseq, keeping personal markdown files on your own hard drive.
- Repurpose an aging Windows laptop that can’t run modern bloatware by flashing a lightweight Linux distribution (like Linux Mint or Fedora). You suddenly gain a distraction-free terminal and writing machine that runs smoothly for another four years.
You don’t just cut your software overhead to zero; you take complete ownership of your data.
7. Combine Micro-Investing with Low-Cost Index Funds
There has been an explosion of modern retail apps offering micro-investing tools that round up spare change from purchases to buy fractional shares. While round-up mechanics can help beginners build an initial saving habit, relying exclusively on them is like trying to fill an Olympic pool with an eyedropper. Worse, some charge a flat $3 monthly fee, which can silently wipe out returns on a small $150 portfolio.
Use micro-investing platforms only to build momentum. Once that habit sticks, shift capital into broad-market index funds (like total stock market or S&P 500 ETFs) through low-fee brokers like Vanguard, Charles Schwab, or Fidelity.
Keep your expense ratios low—aiming below 0.05%. Paying an extra 0.75% in advisory or mutual fund management fees might sound harmless, but compound that over twenty-five years and it can cannibalize more than a fifth of your total wealth.
8. Maintain a Sensible Digital Asset Allocation (and Avoid the Speculative Hype)
In tech hubs, the temptation to chase volatile trends—from speculative meme tokens to NFT drops—is everywhere. Frugal investors who reach early retirement don’t play roulette with their future. They establish a rigid digital asset allocation and maintain it through every hype cycle.
A balanced allocation framework generally looks something like this:
- 70% to 80% Core Holdings: Broad-market index funds, domestic and international equities, and diversified bonds.
- 10% to 20% Cash Reserves: Kept safe inside a federally insured High-Yield Savings Account for 3–6 months of lean living expenses.
- 0% to 5% Speculative Digital Assets: If you choose to hold crypto assets like Bitcoin or Ethereum, cap them at an amount that wouldn’t alter your lifestyle if it plummeted overnight.
Keep your speculative plays small. True financial security comes from predictable compounding, not betting your emergency fund on digital lottery tickets.
9. Introduce a Mandatory 72-Hour Digital Friction Buffer
E-commerce checkout funnels are masterpieces of behavioral psychology. One-click checkouts, autofill credit card credentials, push notifications, and targeted algorithmic feeds work together to turn a passing whim into a processed order in under fifteen seconds.
Frugal people fight back by intentionally introducing friction:
- Strip Payment Autofill: Delete stored payment credentials from your browser and Apple/Google Pay for shopping sites. Having to manually walk across the room, grab a physical wallet, and type 16 digits stops dozens of late-night impulse buys.
- The 72-Hour Rule: When you feel the urge to purchase a non-essential tech accessory, game, or gadget, drop it into your wishlist and set a 72-hour timer.
- Run Ad-Blockers and Unsubscribe: Install content blockers (like uBlock Origin) and strip marketing newsletters out of your inbox using tools like LeaveMeAlone. If you don’t see the flash sale, your dopamine won’t spike, and you won’t spend.
Nine times out of ten, once that initial dopamine hit fades, you’ll realize you didn’t actually want the item in the first place.
10. Anchor Daily Decisions to the FIRE Movement Mindset
The FIRE movement (Financial Independence, Retire Early) isn’t just about quitting work at age 35 to live in a camper van. At its core, it offers a radical perspective on money: Money equals stored life energy.
When you earn $30 an hour after taxes, a shiny new $300 gadget isn’t just three hundred bills. It represents ten uninterrupted hours of your finite life sitting at a desk.
Frugal people who achieve freedom run their spending through this lens:
- “Is this device worth an entire day of my working life?”
- “Does this recurring subscription bring me closer to owning my time, or does it lock me into working longer?”
When you evaluate purchases based on personal freedom rather than immediate status, saying no to superfluous consumer tech stops feeling like a sacrifice. It feels like buying back your future.
:::tip
Expert Insight: The “One-In, One-Out” Tech Rule
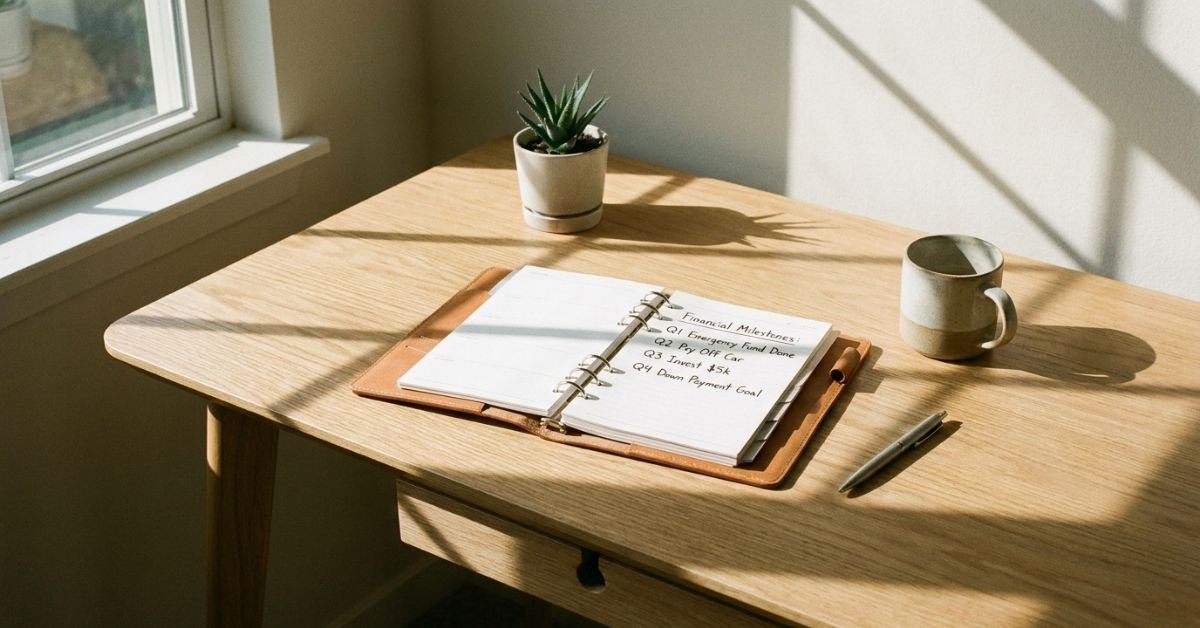
Before adding any new hardware gadget or paid digital subscription to your life, force yourself to retire, sell, or cancel an existing one. If you want a new noise-canceling headset, sell your current pair first and let those proceeds fund the purchase. If you want a specialty cloud backup tool, cancel an existing SaaS seat to make room. This single constraint caps your physical and digital clutter while putting a natural ceiling on ongoing expenses. :::
Frequently Asked Questions
Isn’t tracking every dollar exhausting over the long term?
It only feels exhausting during the first month because you’re breaking old habits. Once you set up an intentional workflow with a zero-based budgeting tool, maintaining it takes about ten minutes a week. You aren’t obsessing over pennies; you’re simply steering your cash so you never have to wonder where it went at the end of the year.
How much should I actually keep in a High-Yield Savings Account?
A solid benchmark is three to six months of baseline survival expenses—rent, groceries, basic utilities, and necessary insurances. If you’re a freelancer or work in a volatile tech sector, bump that cushion to six or nine months. Keep this money strictly parked in an FDIC-insured (or FSCS-insured) HYSA so it earns risk-free yield while staying completely liquid for genuine emergencies.
Does buying refurbished hardware really save money, or is it risky?
Certified refurbished hardware from official manufacturers (like Apple Certified Refurbished, Dell Outlet, or Lenovo Outlet) generally comes with the exact same warranty coverage as brand-new retail units. These machines undergo rigorous bench testing and part replacements before shipping. You typically save 15% to 35% off sticker prices for gear that looks and performs identically to a brand-new machine.
What is the quickest way to tackle SaaS subscription creep?
The most reliable method is the “Statement Purge.” Download the last three months of bank and credit card statements in CSV or PDF format. Highlight every single recurring charge. Cancel anything you haven’t opened in two weeks. If you find yourself missing the service down the road, you can always reactivate it later with zero penalty.
Can micro-investing replace an employer-sponsored retirement account?
No. Micro-investing is a helpful psychological stepping stone for beginners, but it lacks the tax advantages and scale of registered accounts. Always maximize any employer 401(k) match first—that is an instant 100% return on your money—before funding tax-advantaged individual accounts (like a Roth IRA or HSA) and low-cost index funds.










