Debt Avalanche Method Step by Step: Fast Debt Payoff.Three years ago, I stared at a spreadsheet that made my stomach churn: $28,400 across four separate credit cards, an aggressive auto loan, and a nagging consolidation loan.
- 1. 1. Understanding the Debt Avalanche Algorithm and Core Logic Formulas
- 2. 2. Centralizing Your Liabilities with Modern FinTech Tools
- 3. 3. Step-by-Step Guide to Ordering Debts by APR
- 4. Step 1: Extract the Critical Metrics
- 5. Step 2: Sort the Stack
- 6. Step 3: Determine Your Monthly Debt Budget
- 7. 4. Automating Baseline Minimums and Surplus Overpayments
- 8. Lock in Defensive Automated Payments
- 9. Deploying the Surplus
- 10. 💡 Pro Tip: The Interest-Velocity Hack
- 11. 5. Real-World Adjustments: Variable Rates and Promotional Windows
- 12. The Expiring 0% APR Balance Transfer Trap
- 13. Variable Index Benchmarks
- 14. Where Does Debt Consolidation Fit?
- 15. 6. Troubleshooting Pitfalls and Overcoming Motivation Lapses
- 16. 1. Track Interest Saved, Not Just Balances Eliminated
- 17. 2. The Micro-Snowball Circuit Breaker
- 18. Frequently Asked Questions
- 19. What happens when two debts have the exact same APR?
- 20. Should I build an emergency fund before starting the debt avalanche?
- 21. Does the debt avalanche method hurt my credit score?
- 22. Can I run the debt avalanche method while making irregular freelance income?
Every single month, I was throwing $800 into the void, yet my total balances barely budged. Why? Because over $420 of that cash was getting swallowed whole by brutal, compounding interest charges.
Traditional finance advice told me to clear the smallest balance first to get a quick dopamine hit. I tried that for six months. It felt great for about a week until I calculated how much cash I was torching on my 24.99% card while celebrating paying off a tiny 6% medical bill.
Math doesn’t care about feelings. If you want to stop hemorrhage-level cash burn, you need the debt avalanche method. Here is how it works, how the algorithm saves you thousands, and the exact tech stack you can use to automate the entire process from day one.
1. Understanding the Debt Avalanche Algorithm and Core Logic Formulas
The logic behind the debt avalanche method is ruthlessly efficient: you rank every liability you owe in descending order based strictly on its Annual Percentage Rate (APR). You then channel every available discretionary dollar toward the single account holding the highest APR, while maintaining absolute minimum baseline payments on everything else.
Compare this to the Debt Snowball Method. The snowball strategy targets the smallest principal balance first, prioritizing psychological wins over mathematical efficiency. While the snowball works for people who need constant emotional reinforcement to avoid giving up, it comes at a steep financial penalty.
When you service a lower-APR debt first, your high-APR credit card debt continues to compound unchecked. Compounding interest works against you in reverse loan amortization: the higher your balance on an expensive line of credit, the more of your monthly payment goes toward financing costs rather than lowering your actual principal balance.
💰 More Cheap Living Tips You'll Love
- Save Money or Pay Off Debt First? Tech-Driven Guide
- How Long to Pay Off Debt? Tech Tools to Find Out Fast
- Lower Your Electric Bill as a Renter: 12 Cheap Tech Ways
- First Steps to Take When You Decide to Get Out of Debt
- Debt Snowball Worksheet: How to Fill It Out Correctly
- Debt Snowball Method: How It Works (With Real Example)
Daily Interest Calculation Formula:
Daily Interest = (Principal Balance × APR) / 365
Monthly Finance Charge = Daily Interest × Billing Cycle Days
Let’s look at the raw numbers. If you hold $10,000 on a card at 26% APR and $2,000 on an installment loan at 7% APR, the 26% card generates roughly $213.70 per month in raw financing fees alone. By crushing the 26% monster first via the avalanche approach, you extinguish the fastest-growing fire in your portfolio. You reclaim that monthly interest bleed, turning it into surplus payment velocity for the next debt down the stack.
2. Centralizing Your Liabilities with Modern FinTech Tools
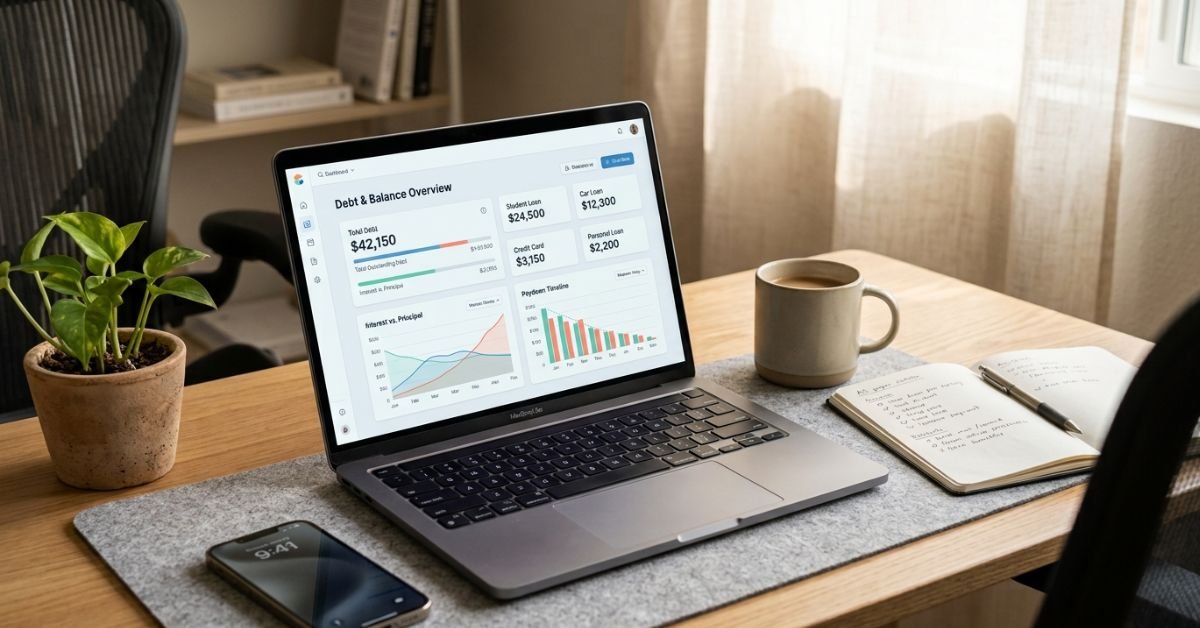
The biggest friction point in tackling multiple loans is bad data. Relying on paper statements arriving on staggered dates causes missed deadlines and calculation blind spots. To run an effective avalanche, you must pull all liabilities into a real-time, unified dashboard.
Instead of logging into five bank portals every week, leverage modern fintech apps and open-banking aggregators:
- Tiller Community Solutions: If you love spreadsheets, Tiller hooks directly into financial aggregators (like Plaid and Yodlee) to automatically populate Google Sheets or Microsoft Excel with daily updated balances and APR rates.
- Monarch Money or Copilot Money: Fantastic standalone personal finance software options that track real-time loan amortization, calculate your overall credit utilization ratio, and warn you about impending rate updates.
- Undebt.it: A purpose-built, browser-based debt payoff platform that lets you toggle instantly between avalanche, snowball, and custom hybrid algorithms without forcing you to re-enter account data.
[Bank APIs / Plaid Feeds]
         │
         ▼
[Central Engine: Tiller / Monarch / Undebt.it]
         │
         ├── Credit Card A (28.99% APR) ──> [Target for Surplus]
         ├── Credit Card B (19.49% APR) ──> [Minimum Auto-Pay]
         └── Personal Loan (8.50% APR)  ──> [Minimum Auto-Pay]
Connecting your liabilities to an API-driven engine removes the manual labor of updating balances. When a statement cuts, your dashboard reflects the true principal balance instantly.
3. Step-by-Step Guide to Ordering Debts by APR
Now let’s build your active hit list. Grab the latest statement for every single liability you carry. Do not guess your APRs—promotional rates expire, penalty rates kick in, and variable rates adjust alongside central bank benchmarks.
Step 1: Extract the Critical Metrics
Create a table with five specific columns:
- Creditor / Account Name
- Current Principal Balance
- True Annual Percentage Rate (APR)
- Minimum Monthly Required Payment
- Monthly Due Date
Step 2: Sort the Stack
Sort the entire list from the highest APR at the top to the lowest APR at the bottom. The balance size is completely irrelevant for sorting; only the interest rate matters.
| Priority | Creditor / Account | Balance | APR (%) | Minimum Due | Allocation Strategy | | :— | :— | :— | :— | :— | :— | | Target 1 | Store Credit Card | $3,200 | 29.99% | $95 | Minimum + All Surplus | | Target 2 | Primary Credit Card | $8,500 | 21.49% | $210 | Minimum Only | | Target 3 | Unsecured Personal Loan | $5,000 | 11.25% | $160 | Minimum Only | | Target 4 | Auto Financing Loan | $14,000 | 5.49% | $320 | Minimum Only |
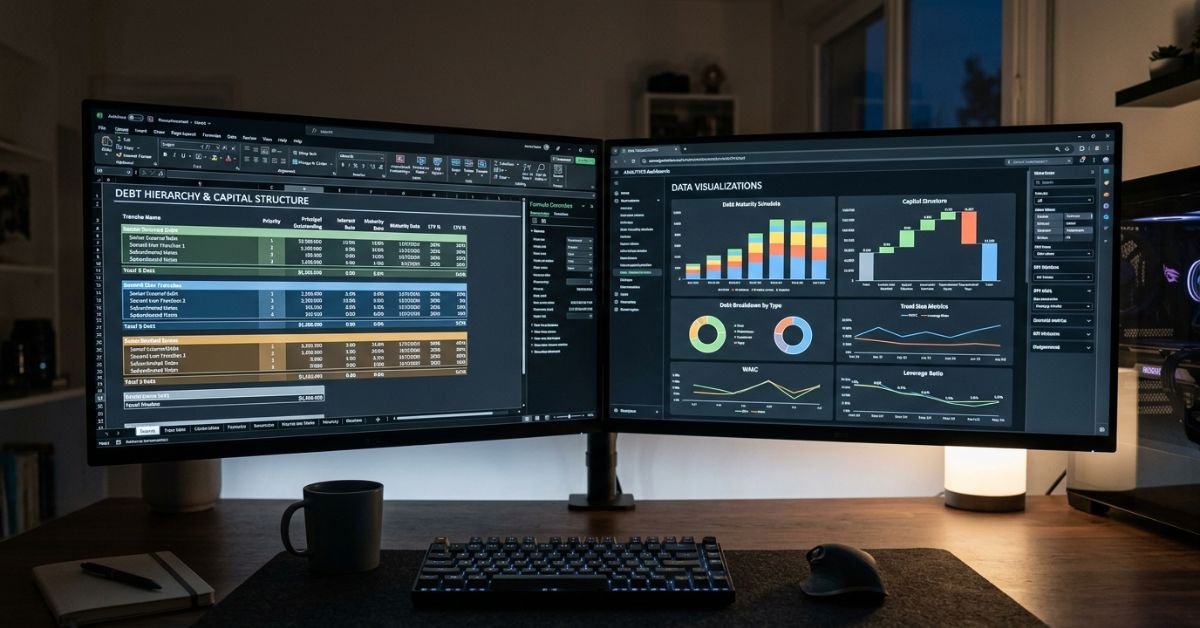
Step 3: Determine Your Monthly Debt Budget
Calculate your non-negotiable living expenses (rent/mortgage, utilities, food) against your net take-home pay.
Subtract the sum of all your minimum debt payments ($785 in the example above). Whatever discretionary cash remains becomes your Surplus Avalanche Capital. If you have an extra $500, your entire $500 surplus goes to Target 1 (making its total payment $595), while Targets 2 through 4 receive strictly their baseline minimums.
4. Automating Baseline Minimums and Surplus Overpayments
Manual payments fail because human memory is unreliable. A single missed due date triggers late fees ($35 to $50) and can skyrocket your APR to a penalty rate exceeding 29.99%, erasing weeks of financial headway.
Lock in Defensive Automated Payments
Log in to every account on your list (Targets 2, 3, and 4) and configure automated payments directly through your bank or the creditor portal. Set these payments to trigger three business days before the official statement due date for the exact minimum balance required.
This automation keeps your accounts current, eliminates delinquency risks, and steadily improves your credit utilization ratio over time.
Deploying the Surplus
For your primary target (Target 1), you have two practical execution methods:
- Split Payments (Bi-Weekly Trigger): If you get paid every other Friday, set up an automated transfer to Target 1 of half the minimum plus half the surplus on your payday. Because credit card interest compounds daily based on your average daily balance, sending money early in the billing cycle reduces total interest accrued.
- The Single-Burst Manual Push: Keep your regular minimum on auto-pay for Target 1, but manually send your variable surplus cash on the day your paycheck clears. This method works best if your monthly income fluctuates (freelancers, contractors, commission-based sales).
💡 Pro Tip: The Interest-Velocity Hack
If you make an extra payment on an installment or auto loan, ensure the creditor tags the overpayment as a “Principal-Only Reduction”.
Many retail banks automatically apply extra funds to “Next Month’s Due Date” by default, effectively holding your capital in escrow without immediately reducing the compounding principal balance that calculates future interest charges. Check your transaction receipts to verify.
5. Real-World Adjustments: Variable Rates and Promotional Windows
Real-world financial scenarios are rarely static. Three common edge cases can disrupt your avalanche stack if you don’t adjust your tracking formulas:
The Expiring 0% APR Balance Transfer Trap
Many people use balance transfer cards featuring a 0% promotional window for 12 to 18 months.
Where does this sit on your avalanche list? While the rate is 0%, mathematically it sits at the bottom of the pile. But you must look out for the deferred interest clause. Certain retail and balance transfer cards charge retroactive interest on the original starting balance if a single dollar remains unpaid when the promotional window closes.
The Fix: Calculate the exact monthly payment needed to zero out the balance one month before the promo expires (Balance / (Months Remaining - 1)). Hard-code this figure as a non-negotiable fixed minimum payment in your tracker, treating it as an operational expense rather than a variable avalanche target.
Variable Index Benchmarks
Most credit card debt runs on variable rates tied directly to prime rates. When central banks shift interest rates, your credit card APR adjusts upward, sometimes within one to two billing cycles.
Re-audit your APR column every quarter. A loan you thought was sitting comfortably in spot #3 might leapfrog into spot #2 after a series of rate increases.
Where Does Debt Consolidation Fit?
If your credit score remains relatively healthy (usually above 670), applying for an unsecured debt consolidation loan can make mathematical sense.
Swapping three credit cards running at an average of 24% APR for a fixed-rate personal loan at 9.5% dramatically lowers your aggregate financing expenses. Once consolidated, plug the new personal loan into your existing avalanche sheet based on its new 9.5% rate and continue your downward march.
6. Troubleshooting Pitfalls and Overcoming Motivation Lapses
The biggest risk of the debt avalanche method isn’t mathematical; it’s psychological.
If your highest-APR account happens to be an enormous $18,000 credit card balance, you could funnel $600 of surplus cash into it every month for nearly two years without completely crossing a single account off your hit list. That lack of tangible completion creates “avalanche fatigue.”
Here is how to keep your momentum alive when the math feels slow:
1. Track Interest Saved, Not Just Balances Eliminated
Standard finance apps celebrate when an account hits zero balance. When using the avalanche, that milestone takes longer.
Instead, track your Monthly Interest Savings. In your spreadsheet, compute the total interest charged this month compared to your starting baseline month:
Monthly Savings = Baseline Month Total Interest - Current Month Total Interest
Watching your monthly financing charges drop from $450 to $280, then down to $110, provides immediate, tangible proof that your strategy is working. You are physically clawing back cash from the bank’s pockets.
2. The Micro-Snowball Circuit Breaker
If you have been grinding against an enormous top-tier account for eight straight months and feel your discipline cracking, execute a temporary “circuit breaker.”
Look down your list. Do you have a tiny $350 medical bill or a $400 store card balance sitting further down the pile? Pause the avalanche surplus for a single month, wipe out the small annoyance in one swift payment, and cross it off the board.
Yes, you sacrifice a tiny bit of mathematical purity. But the psychological reboot of eliminating a physical statement from your inbox can replenish the willpower required to dive back into your primary high-APR target.
Frequently Asked Questions
What happens when two debts have the exact same APR?
If two accounts carry identical interest rates (for example, two credit cards both sitting at 22.99% APR), break the tie by targeting the account with the smaller principal balance first. This temporarily integrates a snowball benefit into your avalanche framework: you eliminate one minimum payment obligation faster, freeing up monthly cash flow and simplifying your management overhead.
Should I build an emergency fund before starting the debt avalanche?
Yes, but keep it lean. Aim for a micro-emergency buffer of roughly one month of essential living expenses (typically between $1,000 and $2,500 depending on your regional cost of living) stashed in a high-yield savings account before throwing every spare dollar at high-APR debt.
Without this cash buffer, an unexpected car repair or emergency dental visit will force you right back onto the high-interest credit lines you are trying to pay off.
Does the debt avalanche method hurt my credit score?
No, it actually optimizes it over the long term. By aggressively reducing your highest-APR credit card balances, you directly lower your overall credit utilization ratio, which accounts for roughly 30% of your standard credit scoring profile.
As your balances drop below key utilization thresholds (under 30%, and ideally under 10% of your total limits), your credit scores will reflect that improvement. Just make sure to leave those paid-off credit card accounts open to preserve your total available credit limit and credit history length.
Can I run the debt avalanche method while making irregular freelance income?
Absolutely. The safest approach is to budget your monthly baseline minimum payments around your baseline lowest-earning month. Automate those minimum payments to maintain account safety.
Whenever you receive invoice payouts, project completions, or quarterly bonuses, immediately push 50% to 70% of that variable windfall as an ad-hoc manual surplus payment directly toward your highest-APR account before lifestyle inflation absorbs it.