Is It Better to Save or Pay Off Debt First? A Tech-Driven Decision Guide.A couple of years back, I found myself staring at two open browser tabs late on a Sunday night. Tab one showed my brand-new High-Yield Savings Account (HYSA) sitting at an attractive 4.5% yield. Tab two displayed an outstanding balance of $6,400 on a travel credit card with a brutal 22.49% Annual Percentage Rate (APR)—the lingering ghost of an emergency home lab server upgrade and an unexpected flight home.
- 1. The Mathematical Dilemma: APR vs. APY Algorithms Explained Tech-Style
- 2. The Tax Drag Most People Forget
- 3. The Tech-Driven Hybrid Model: Starter Emergency Funds Before Aggressive Payoff
- 4. Establishing Your Liquidity Sandbox
- 5. Pro Tip: The 401(k) Match Exception
- 6. Algorithmic Payoff Strategies: Debt Snowball vs. Debt Avalanche Automated
- 7. Top Fintech Apps to Automate the Save vs. Pay Off Choice
- 8. 1. Undebt.it
- 9. 2. You Need A Budget (YNAB)
- 10. 3. Monarch Money
- 11. The Pitfall of Broken Aggregator Feeds
- 12. Common Pitfalls When Prioritizing Savings Over High-Interest Debt
- 13. The Stagnant Cash Trap
- 14. Ruining Your Credit Utilization Ratio
- 15. Frequently Asked Questions
- 16. Should I save or pay off debt first if my interest rate is under 5%?
- 17. What about my employer’s 401(k) match—does that take priority over paying down debt?
- 18. How much should I save while paying off debt?
- 19. Does paying off revolving credit card debt fast help my credit score?
- 20. Is a 0% APR balance transfer card a good tool while building savings?
- 21. The Verdict: How to Allocate Your Next Dollar
I sat there wondering: should I save or pay off debt first?
Every fiber of my tech-oriented brain wanted to hoard liquidity. Cash in the bank feels safe; it feels like an operational buffer against a volatile job market. Yet the pure mathematics of compound interest told an entirely different story.
If you are stuck between padding a digital savings vault and annihilating your credit card balance, you are dealing with one of the most common resource allocation problems in personal finance. Let’s break down the math, build an algorithmic strategy, and look at the exact fintech tools you can use to automate the entire process.

The Mathematical Dilemma: APR vs. APY Algorithms Explained Tech-Style
When we treat personal finances like an engineering optimization problem, the dilemma of whether to pay off high interest debt vs invest or save boils down to a comparison of rates of return.
Let’s unpack the core metrics:
- Annual Percentage Rate (APR): The annualized cost of borrowing money, calculated as simple interest plus basic fees. On revolving credit like credit cards, interest compounds daily based on your average daily balance.
- Annual Percentage Yield (APY): The real rate of return earned on a savings deposit, taking the compounding frequency into account.
Currently in the United States, Federal Reserve interest rates have settled at levels that create an interesting dynamic. You can easily find an FDIC-insured High-Yield Savings Account (protecting deposits up to $250,000 per depositor, per institution) on platforms like Marcus by Goldman Sachs, Ally Bank, or Wealthfront paying between 4.0% and 5.0% APY.
💰 More Cheap Living Tips You'll Love
- Debt Snowball Worksheet: How to Fill It Out Correctly
- Debt Snowball on a Low Income: Does It Still Work in 2026-27?
- Debt Snowball Method: How It Works (With Real Example)
- How Long to Pay Off Debt? Tech Tools to Find Out Fast
- Lower Your Electric Bill as a Renter: 12 Cheap Tech Ways
- Debt Snowball vs Avalanche: Which Repayment Strategy Wins?
That looks great on paper until you contrast it with the American credit card landscape. According to Federal Reserve data, the average US credit card APR hovers around 21% to 24%.
[4.5% APY Gross HYSA Yield] - [~25% Marginal Tax Bracket] = ~3.37% Net Return
vs.
[22.49% Revolving Credit APR] = -22.49% Guaranteed Loss

Net Spread: An immediate -19.12% drag on your net worth.
The Tax Drag Most People Forget
Here is the kicker that standard financial calculators often overlook: taxes.
Interest earned from a high-yield savings account is taxed as ordinary income at both the federal and state levels. If you earn $500 in interest from an HYSA and sit in the 24% federal tax bracket (plus, say, 5% state tax), Uncle Sam and your state take nearly $145 of that gain. Your effective yield drops to roughly 3.2%.
Conversely, paying off a 22.49% revolving credit line offers an instant, risk-free, tax-exempt return of 22.49%. No stock index, no certificate of deposit (CD), and certainly no traditional savings account can beat that risk-adjusted hurdle rate.
If your primary question is simply about a high yield savings account vs paying off loan balances with double-digit rates, the math yields an indisputable answer: the high-interest debt must die.
The Tech-Driven Hybrid Model: Starter Emergency Funds Before Aggressive Payoff
Pure math suggests dumping every single available dollar into your highest-APR balance immediately. If you have $4,000 in cash and $4,000 in credit card debt, math says zero out the card today.
In the real world, human systems crash without memory buffers.
If you drain your checking and savings accounts down to absolute zero to clear a balance, you leave yourself zero fault tolerance. When your car’s transmission drops or your MacBook’s logic board fails—demanding an immediate $1,200 repair—you have no liquid cash. You are forced to swipe that credit card again.
This creates a demoralizing psychological loop: save, dump into debt, hit an emergency, swipe the card, repeat.
       [Monthly Income]
              │
              ▼
   ┌──────────────────────┐
   │ 401(k) Employer Match│ ──► Grab the 100% instant ROI first
   └──────────────────────┘
              │
              ▼
   ┌──────────────────────┐
   │ Starter Emergency    │ ──► $1,000 - $2,000 buffer in HYSA
   │ Liquidity Buffer     │     (Prevents swiping cards for surprises)
   └──────────────────────┘
              │
              ▼
   ┌──────────────────────┐
   │ Aggressive Debt      │ ──► Avalanche Method for toxic debt (>7%)
   │ Repayment Engine     │
   └──────────────────────┘
              │
              ▼
   ┌──────────────────────┐
   │ Full Emergency Fund  │ ──► Scale to 3-6 months living expenses
   │ & Long-Term Growth   │     (HYSA + Roth IRA + Index Funds)
   └──────────────────────┘
Establishing Your Liquidity Sandbox
Before going on an aggressive debt payoff campaign, build a mini emergency fund. For most folks living in the US, a baseline buffer between $1,000 and $2,000 works wonders.
- Keep it separate: Do not let this cash sit in your primary checking account where it gets eaten by everyday spending.
- Put it in a digital vault: Use the “Buckets” feature in Ally or “Vaults” inside SoFi.
- Automate micro-deposits: Program a rule through your bank or a fintech automation app to move $100 every Friday until that starter buffer hits its target.
Once that sandbox is funded, halt extra savings contributions temporarily. Channel every spare cent of discretionary cash flow straight into clearing toxic balances.
Pro Tip: The 401(k) Match Exception
Never bypass your employer’s 401(k) match to pay off debt. If your employer offers a 100% match on the first 4% or 5% of your salary, that represents an instant 100% return on investment. Not even a 28% credit card penalty rate beats an instantaneous 100% match. Contribute just enough to capture the full match, build your starter cash buffer, and then attack the debt.
Algorithmic Payoff Strategies: Debt Snowball vs. Debt Avalanche Automated
Once you have your emergency buffer running, how do you determine the best way to pay off credit card debt fast? In computer science, choosing the right sorting algorithm dictates performance. Repaying debt is no different.
You generally have two dominant strategies:
- The Debt Avalanche (The Mathematical Optimizer): You order all your debts in descending order by interest rate (APR). You make minimum payments on all accounts and throw every surplus dollar at the account with the highest APR.
- The Debt Snowball (The Psychological Behavioral Hack): You order debts in ascending order by total balance, ignoring interest rates entirely. You target the smallest balance first to score quick behavioral wins.

Let’s look at a realistic scenario running through a debt avalanche vs snowball calculator model:
- Card A: $2,500 balance at 24.99% APR (Min payment: $65)
- Card B: $8,200 balance at 19.99% APR (Min payment: $190)
- Personal Loan: $1,500 balance at 9.50% APR (Min payment: $50)
- Available Monthly Allocation: $800 total
| Strategy | Payoff Priority | Time to Debt Freedom | Total Interest Paid | | :— | :— | :— | :— | | Debt Snowball | Personal Loan → Card A → Card B | ~19 Months | ~$1,840 | | Debt Avalanche | Card A → Card B → Personal Loan | ~18 Months | ~$1,495 |
The Avalanche method saves roughly $345 in cold, hard cash and shaves off a month of payments because it neutralizes the compounding power of Card A’s 24.99% interest rate right away.
However, if clearing that $1,500 personal loan in month two gives you the motivational spark to keep going without quitting, the Snowball method has real human merit. Pick the algorithm you can execute consistently without abandoning ship.
Top Fintech Apps to Automate the Save vs. Pay Off Choice
Managing split-priority finances manually across multiple spreadsheets is a fast track to burnout. Fortunately, algorithmic budgeting tools and open-banking APIs can handle the heavy lifting for you.
1. Undebt.it
If you want granular control over your debt prioritization algorithm, Undebt.it is fantastic. It is a dedicated debt engine that lets you toggle between Avalanche, Snowball, or custom hybrid algorithms with a single click.
- Tech Highlight: It syncs directly with budgeting apps through an API and visually charts your projected debt-free date based on variable monthly overpayments.
2. You Need A Budget (YNAB)
YNAB uses zero-based envelope budgeting to force you into allocating every dollar of income toward a distinct job.
- Tech Highlight: Its credit card handling logic is top-tier. When you assign money to an expense (like groceries), YNAB automatically shifts that cash into your credit card payment category so you never accidentally add new debt while paying down old balances.
3. Monarch Money
Monarch is modern, sleek, and powered by multiple data aggregators (Plaid, MX, and Finicity).
- Tech Highlight: If an account drops connection or your credit card company quietly hikes your interest rate following a Federal Reserve rate adjustment, Monarch highlights balance fluctuations across your net worth graph instantly.
┌────────────────────────────────────────────────────────┐
│             Fintech Automation Workflow                │
├────────────────────────────────────────────────────────┤
│ 1. Direct Deposit splits paycheck automatically:       │
│    ├── 85% to Main Checking (Bills & Operations)       │
│    └── 15% to High-Yield Savings Account (Liquid Vault)│
│                                                        │
│ 2. Main Checking triggers automated bill-pay rules:    │
│    ├── Minimum payments to Low-APR lines               │
│    └── Maximum automated surplus to Target Card        │
│                                                        │
│ 3. API alerts (Plaid/MX) warn if utilization hits 30%  │
└────────────────────────────────────────────────────────┘
The Pitfall of Broken Aggregator Feeds
One warning from someone who has linked dozens of bank accounts to fintech tools: never set-and-forget third-party connections completely. Banks frequently rotate their security protocols, which can quietly break background open-banking syncs.
If Plaid disconnects from your primary card, an automated payment could misfire, leaving you with a missed payment fee and a hit to your credit score. Check your dashboard once a week to confirm transactions are logging cleanly.
Common Pitfalls When Prioritizing Savings Over High-Interest Debt
Navigating this trade-off comes with several quiet traps that can set your net worth back by years.
The Stagnant Cash Trap
The biggest mistake I routinely see is keeping thousands of dollars sitting in a traditional checking or savings account earning 0.01% at a legacy brick-and-mortar bank while juggling high-interest balances. If you have $10,000 parked in an account returning essentially zero interest while carrying $8,000 of debt at 21% APR, you are quietly paying roughly $140 a month for the privilege of looking at cash on a screen.
Deploy that cash. Keep your starter emergency fund, keep one month of living expenses in checking as a working buffer, and use the rest to destroy high-rate balances.
Ruining Your Credit Utilization Ratio
Your Credit Utilization Ratio makes up roughly 30% of your FICO credit score. This metric measures the amount of revolving credit you are currently using divided by your total credit limits.
- If your card has a $5,000 limit and you carry a $4,500 balance, your utilization is sitting at an alarming 90%.
- Even if you are saving money on the side, that sky-high utilization drags down your credit profile, disqualifying you from 0% APR balance transfer promotions that could otherwise accelerate your debt repayment.
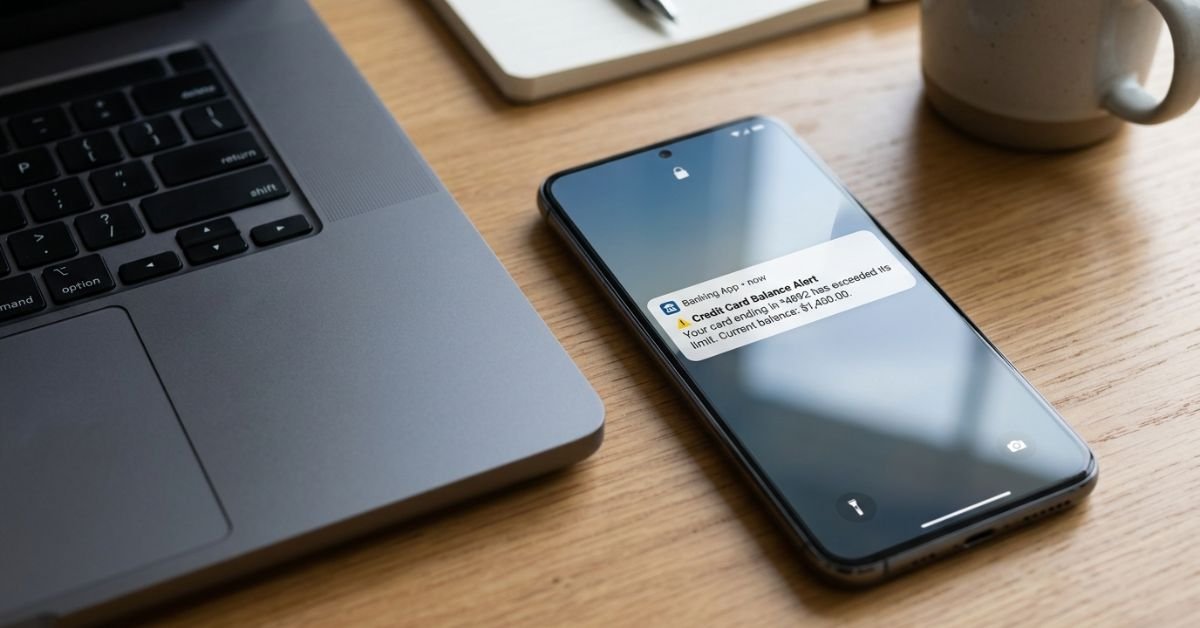
- Actionable Step: Set automated push notifications across your card accounts to alert you whenever your balance crosses 30% of your credit limit.
Frequently Asked Questions
Should I save or pay off debt first if my interest rate is under 5%?
If your debt is low-rate, fixed debt—such as an older federal student loan, an auto loan under 4%, or a low-rate mortgage—saving or investing often beats paying it off early. If you can earn 4.5% to 5.0% in an FDIC-insured High-Yield Savings Account, or a historical average of 7% to 10% through a broad-market index fund inside a Roth IRA, your capital works harder compounded in those vehicles than it does paying down cheap debt.
What about my employer’s 401(k) match—does that take priority over paying down debt?
Yes. An employer match is typically a dollar-for-dollar (100%) or 50% immediate return on your contributed funds. There is no debt on the open market with an interest rate high enough to beat an instant 50% or 100% return. Always capture your full company match before funneling spare cash toward debt balances.
How much should I save while paying off debt?
While actively paying down high-interest credit card debt, limit your savings to a basic starter emergency fund—usually between $1,000 and $2,000. Stashing away more than that while carrying debt at 20%+ APR costs you substantial interest. Once all toxic, double-digit interest debt is eradicated, scale that savings balance up to a full three to six months of living expenses.
Does paying off revolving credit card debt fast help my credit score?
Yes, significantly. Paying down revolving credit balances lowers your overall credit utilization ratio. Because utilization has no historical memory under standard scoring models like FICO 8, reducing your balance from 80% to under 10% can trigger an immediate, noticeable jump in your credit score within one to two billing cycles.
Is a 0% APR balance transfer card a good tool while building savings?
A 0% intro APR balance transfer card can be a powerful engineering shortcut. It allows you to move high-interest balances to a new card with 0% interest for an introductory window (typically 12 to 21 months), usually for an upfront transfer fee of 3% to 5%. This stops compounding interest in its tracks, letting every payment directly reduce principal while you simultaneously build your emergency cash reserves.
The Verdict: How to Allocate Your Next Dollar
When evaluating whether to save money or eradicate debt, ditch emotional guesses and run the numbers through this sequential hierarchy:
- Fund your baseline buffer: Put $1,000 to $2,000 into a high-yield savings account for unexpected operational shocks.
- Claim your 401(k) match: Capture 100% of any available employer matching funds.
- Crush toxic debt (>7% APR): Deploy the debt avalanche strategy to destroy revolving credit cards and high-rate personal loans.
- Build your fortress: Once toxic debts hit zero, redirect those monthly payments back into your HYSA until you hold three to six months of true baseline living expenses.
- Invest for long-term growth: Open the throttle on retirement vehicles like your Roth IRA, traditional 401(k), and low-cost taxable index funds.
Treat your personal finances like an evolving tech stack: eliminate system bugs (high-interest debt), maintain an operational cache (emergency funds), and optimize for maximum long-term output.