Debt Snowball on a Low Income: Does It Still Work Today? A few years ago, I sat at a kitchen table across from a single mother named Elena. She was bringing home roughly $2,600 a month working as an administrative assistant in suburban Cleveland. Spread out between us were three credit card statements, an unpaid ambulance bill from an ER visit nine months prior, and an auto loan statement on a 2014 Civic that was teetering dangerously close to negative equity. Her question was blunt: “Every personal finance guru tells me to use the debt snowball, but how am I supposed to roll a snowball when there isn’t any snow?”
- 1. How the Debt Snowball Operates on a Limited Budget
- 2. The Mechanics with Restricted Cash Flow
- 3. Debt Snowball vs Avalanche Low Income: The Real-World Breakdown
- 4. How to Do Debt Snowball When Broke (The Step-by-Step Blueprint)
- 5. Step 1: Secure a Micro-Emergency Buffer
- 6. Step 2: Stop the Bleed and Stabilize
- 7. Step 3: Shift to Bi-Weekly Micro-Payments
- 8. Step 4: Harvest “Invisible Money”
- 9. Modernizing Your Strategy: The Low-Income FinTech Toolkit
- 10. 1. Undebt.it (The Best Free Debt Snowball Calculator)
- 11. 2. Zero-Based Budgeting Tools
- 12. 3. Automated Micro-Saving & Micro-Investing
- 13. 💡 Pro Tip: The “Reverse Micropayment” Technique
- 14. Dealing with Medical Debt, Collections, and US Regulations
- 15. Medical Debt Protections
- 16. Handling Aggressive Collectors via the FDCPA
- 17. Frequently Asked Questions
- 18. What if I cannot even afford the minimum payments on all my debts?
- 19. Should I keep contributing to a 401(k) while doing the debt snowball?
- 20. How does the debt snowball impact my credit score?
- 21. Is consolidation a better route than the snowball for low incomes?
- 22. Can I include my student loans in the debt snowball?
- 23. Moving Forward Without Falling Back
It is the question millions of working Americans ask every week. When you look at classic personal finance media—the loud radio hosts, the bestsellers preaching radical frugality—the underlying assumption is almost always that you have a spending problem, not an income problem. They tell you to cut the lattes, sell everything in sight, and throw an extra $500 a month at your smallest balance.
That advice sounds great if you pull in six figures and blow money on luxury subscriptions. It feels like an insult when you are trying to figure out how to pay off debt on 30k a year while rent eats half your take-home pay, groceries cost 30% more than they did three years ago, and high gas prices eat up whatever is left.
Over the past decade, our team has coached dozens of households through more than $500,000 in collective consumer debt payoff. We have stress-tested budgeting apps, tested every automated savings tool, and run spreadsheets until our eyes crossed.
The short answer? Yes, the debt snowball method still works on a tight budget. But it does not work the way traditional financial radio hosts claim it does. You cannot just use sheer willpower when your checking account is hovering at $43.50 two days before payday. You have to modernize the process using modern cash flow management, digital micro-payments, and a cold-eyed look at the math.

How the Debt Snowball Operates on a Limited Budget
At its core, popularized by figures like Dave Ramsey, the debt snowball is dead simple: you list your debts from smallest balance to largest balance, regardless of the Annual Percentage Rate (APR). You make the minimum payment on everything except the smallest account, and you throw every available cent at that tiny balance until it’s wiped out. Once it’s gone, you take everything you were paying toward it and roll it into the next smallest debt.
The mechanism is psychological. When you kill off an account completely, your brain gets a dopamine hit. You feel momentum. You feel like winning is possible.
💰 More Cheap Living Tips You'll Love
- Lower Your Electric Bill as a Renter: 12 Cheap Tech Ways
- Debt Snowball Worksheet: How to Fill It Out Correctly
- First Steps to Take When You Decide to Get Out of Debt
- Debt Snowball Method: How It Works (With Real Example)
- Debt Avalanche Method Step by Step: Fast Debt Payoff
- How Long to Pay Off Debt? Tech Tools to Find Out Fast
The Mechanics with Restricted Cash Flow
When your household income is under $40,000, however, standard snowballing hits immediate friction:
- The “Extra Money” Myth: Most snowball guides assume an extra $100 to $300 a month is floating around. On low income, an extra $15 might be your absolute ceiling.
- The Danger of Overdrafts: Aggressively sending lump sums to a credit card early in the month leaves you vulnerable to unpredictable expenses. If your water bill spikes or your child needs medicine, you run the risk of overdrafting your checking account—triggering a cascade of $35 bank fees that destroy your progress.
- Predatory Fallbacks: When unexpected bills hit and cash is drained, the temptation to use a payday advance or an auto title loan becomes immense. Those loans carry triple-digit interest rates that turn a minor setback into a multi-year spiral.
To make the debt snowball method paycheck to paycheck sustainable, you must redefine what an “extra payment” looks like. It is no longer a $200 monthly check. It is four $15 transfers timed meticulously to clear right after your direct deposit hits.
Debt Snowball vs Avalanche Low Income: The Real-World Breakdown
In pure financial theory, the debt avalanche wins every single time. With the avalanche method, you list your debts by interest rate (highest APR first). Mathematically, targeting a 28.99% store card saves you far more money than paying off an interest-free $400 medical bill.
So why do we frequently recommend the snowball method when working with lower-income households?
+--------------------------+-------------------------------------+-------------------------------------+
| Feature                  | Debt Snowball                       | Debt Avalanche                      |
+--------------------------+-------------------------------------+-------------------------------------+
| Primary Focus            | Smallest Balance First              | Highest APR First                   |
| Psychological Impact     | High (Fast, visible wins)           | Low (Can feel like a long slog)     |
| Cash Flow Relief         | Rapid (Eliminates minimums quickly) | Slow (Takes longer to drop a bill)  |
| Mathematical Efficiency  | Lower (You pay more interest)       | Optimal (Minimizes interest paid)   |
| Best For                 | Tight budgets, low cash margins     | Stable income, high discipline      |
+--------------------------+-------------------------------------+-------------------------------------+
When you are living on the edge of every dollar, cash flow flexibility is your armor.
Consider this real scenario: You have four debts:
- A $350 medical bill ($30/mo minimum)
- A $900 retail card at 29% APR ($45/mo minimum)
- A $3,200 Visa card at 21% APR ($95/mo minimum)
- A $7,000 used car loan at 8% APR ($190/mo minimum)
If you use the avalanche method, you attack the 29% retail card. It might take you 9 or 10 months to kill that card on your current margin. During those 10 months, you are still legally obligated to make all four payments every single month ($360 total). If your hours get cut at work, you have four distinct creditors demanding cash.
If you choose the snowball and knock out that $350 medical bill in two months, you eliminate an entire obligation. Your required monthly layout drops from $360 to $330. That newly freed $30 minimum payment can now protect you from an overdraft or be weaponized against the next debt. In a fragile financial ecosystem, lowering your required monthly fixed overhead quickly is often worth the extra interest paid.
How to Do Debt Snowball When Broke (The Step-by-Step Blueprint)
If you are wondering does the debt snowball work with no extra money, the honest answer is: not unless you create a tiny sliver of breathing room first. You cannot pay off debt with magic. You need a surplus, even if that surplus is literally $1.50 a day.
Here is the exact framework we use with clients to build momentum from ground zero:
Step 1: Secure a Micro-Emergency Buffer
Do not start paying extra on debt with a zero-dollar bank balance. If an unexpected bill hits, you will immediately reach for the credit card, breaking your psychological stride.
Open a fee-free high-yield savings account (HYSA) at a bank separate from your primary checking account. Park $500 to $750 there. It is not an investment; it is an insurance policy against your own debt cycle. Don’t worry about saving 3 to 6 months of expenses yet; just build this small cushion.
Step 2: Stop the Bleed and Stabilize
Audit your bank statements from the last 60 days. Look specifically for recurring software subscriptions, membership fees, or sneaky service charges. You do not need to cut your life down to bread and water, but you must identify every single dollar leaving your ecosystem without providing survival value or deep joy.
Step 3: Shift to Bi-Weekly Micro-Payments
Instead of sending one large lump payment at the end of the month, switch your payment strategy to align with your paydays. If you get paid every other Friday, split your minimums into bi-weekly payments and add your extra snowball amount ($10, $20) to the targeted debt on that exact day.
Because credit cards calculate interest on an average daily balance, making smaller, more frequent payments reduces the interest accrued across the month.
Step 4: Harvest “Invisible Money”
- Round-ups: Use accounts or tools that round up purchases to the nearest dollar, sweeping that change into your debt target.
- Cashback Redemption: If you have an active debit card or rewards balance, never let it sit. Cash it out immediately and apply it to your smallest balance.
- Bill Renegotiation: Call your internet service provider, auto insurance broker, and mobile carrier. Ask for retention pricing or move to prepaid carriers (like Mint Mobile, Visible, or Cricket). Taking a phone bill from $90 down to $30 immediately yields $60 a month in direct snowball fuel.
Modernizing Your Strategy: The Low-Income FinTech Toolkit
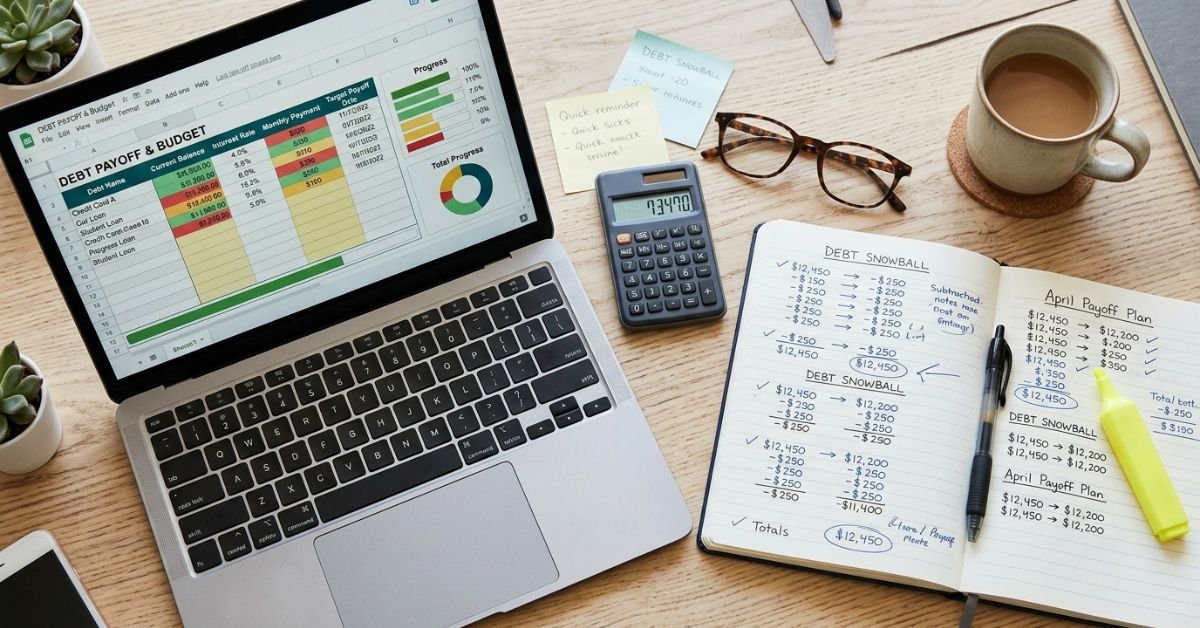
You do not need to buy expensive software or pay a financial coach to track your numbers. Modern financial technology has drastically leveled the playing field for folks on tight budgets.
When searching for a debt snowball method low income app, look for tools that leverage open-banking protocols (like Plaid) safely, without hitting you with high monthly subscription fees.
1. Undebt.it (The Best Free Debt Snowball Calculator)
If you want something robust without paying a penny, Undebt.it remains one of the absolute best options available. It allows you to enter all your balances, APRs, and minimum payments, and compare the snowball method against the avalanche method side-by-side. It recalculates your payoff dates automatically whenever you throw an extra $5 or $10 at an account.
2. Zero-Based Budgeting Tools
Apps like EveryDollar (free version) or Goodbudget (which digitizes the classic envelope method) force you to assign every single dollar a job before the month begins. This ensures you do not accidentally spend your debt snowball allocation on impulse expenses.
3. Automated Micro-Saving & Micro-Investing
While your focus should be primarily on debt, services like Qapital or built-in bank features (like Ally’s Surprise Savings) analyze your checking account patterns and automatically transfer safe, tiny amounts ($1.25 here, $3.10 there) into savings or toward debt payoff. You barely feel the withdrawal, but over 30 days, it creates a $40 to $50 extra debt payment out of thin air.
💡 Pro Tip: The “Reverse Micropayment” Technique
Most people wait until the end of the month to see what cash is left over for their debt snowball. On a low income, the answer is almost always zero.
Instead, link your target debt account directly to your checking account’s online bill-pay. The morning your paycheck clears, immediately send an aggressive, but modest micro-payment—say, $20—to your smallest debt. Treat that $20 like a non-negotiable utility bill. By removing it before you buy groceries or gas, your lifestyle naturally scales to fit the remaining 99% of your paycheck. Two weeks later, do it again.
Dealing with Medical Debt, Collections, and US Regulations
If your debt load includes medical balances or accounts that have already gone to third-party collectors, the rules of the game change. You should not blindly throw precious snowball dollars at these accounts without understanding your rights.
Medical Debt Protections
Thanks to regulatory updates backed by the Consumer Financial Protection Bureau (CFPB) and voluntary changes from the three major credit bureaus (Equifax, Experian, TransUnion):
- Paid medical collection debt is no longer included on consumer credit reports.
- Unpaid medical debt under $500 cannot be reported on your credit file at all.
- Medical bills must undergo a one-year waiting period before appearing on your credit history.
If you have a $300 medical bill, do not prioritize it over high-interest credit cards just because it is your smallest balance. Call the hospital or clinic’s billing department, request their Financial Hardship / Charity Care policy (many non-profit hospitals are legally required to forgive debts for households under 200–400% of the federal poverty line), and negotiate it down to zero or a tiny settlement.
Handling Aggressive Collectors via the FDCPA
When dealing with older debts sold to collection agencies, remember you are protected under the Fair Debt Collection Practices Act (FDCPA). Collectors cannot:
- Call you before 8:00 AM or after 9:00 PM local time.
- Threaten you with arrest or wage garnishment without a court judgment.
- Continue contacting you at work if you state your employer prohibits personal calls.
Never give a collection agency direct electronic access to your main checking account via ACH. If you settle an old balance as part of your snowball, get the agreement in writing first, then pay using a cashier’s check, money order, or a separate digital card (like Privacy.com) to prevent unauthorized balance drains.
Frequently Asked Questions
What if I cannot even afford the minimum payments on all my debts?
If your basic survival needs—housing, utilities, food, and basic transport—exceed your income, you are in an operational deficit. In this scenario, running a debt snowball is mathematically impossible until you stabilize.
Prioritize your “Four Walls” first. Contact your lenders immediately and ask for their internal hardship programs. Most credit card issuers have unadvertised concessions that temporarily slash your APR down to 0% to 9% and reduce minimums for 6 to 12 months. Do not let shame prevent you from asking; banks prefer working with you over sending your account to charge-off status.
Should I keep contributing to a 401(k) while doing the debt snowball?
If your employer offers a 401(k) match, try your best not to walk away from it—it is an instant 50% to 100% return on your money. However, if your debt payments are pushing you toward missed payments or predatory payday loans, it makes practical sense to temporarily pause retirement contributions until you have cleared your highest-risk consumer debts and established a minimal cash buffer.
How does the debt snowball impact my credit score?
Initially, paying off a small account might cause a temporary minor dip depending on the age of the account, but over time, your credit utilization ratio will plummet. Credit utilization makes up roughly 30% of your FICO score. As you knock out accounts one by one, your available credit expands while your balances drop, driving steady, long-term credit score recovery.
Is consolidation a better route than the snowball for low incomes?
Debt consolidation loans only work if two criteria are met: you qualify for an interest rate significantly lower than your current weighted average, and you have resolved the cash flow issue that created the debt initially. On a low income or with a damaged credit profile, consolidation loans often come with high origination fees and predatory interest rates. If you cannot qualify for a prime loan through a reputable local credit union, sticking to a disciplined, self-directed snowball is usually far safer.
Can I include my student loans in the debt snowball?
Yes, but federal student loans should generally sit at the very end of your priority list. Federal loans come with income-driven repayment (IDR) plans, forbearance options, and forgiveness pathways that standard consumer debt does not offer. Keep federal student loans on an IDR plan to keep your monthly required payment as low as possible while you aggressively snowball your credit cards and personal loans.
Moving Forward Without Falling Back
Getting out of debt on a low income is not about grand gestures. It is about staying disciplined through months where progress feels microscopic.
There will be weeks where your transmission slips, your kid needs dental work, or your work hours get cut, temporarily stalling your snowball. That is not failure; that is simply life happening. Because you built a modest cash cushion first, you will absorb those hits without sliding back onto high-interest plastic.
Keep your tracking simple, make your micro-payments automatic, lean on free financial tools, and remember that eliminating even a single $25-a-month minimum payment gives you more breathing room than you had yesterday. Step by step, balance by balance, you will get there.