Smart Bank Account Structuring Strategies to Automate Wealth Building.Back in 2018, I sat at my kitchen table staring at a single checking account balance of $4,350. On paper, I was doing fine. In reality, I was terrified to spend $60 on dinner with friends. Why? Because I had no idea whether that $4,350 was supposed to cover my upcoming car insurance premium, the quarterly water bill, next month’s rent, or my actual grocery money for the week.
- 1. 1. The Psychology of Frictionless Saving: Why Traditional Budgeting Fails and Systems Win
- 2. 2. The 4-Tier Automated Architecture: Organizing Accounts for Maximum Output
- 3. Tier 1: Operational Hub (Everyday Checking)
- 4. Tier 2: Fixed Obligations (Bills Checking)
- 5. Tier 3: Targeted Liquidity (HYSA Sinking Funds)
- 6. Tier 4: The Wealth Engine (Investment Vehicles)
- 7. 3. Step-by-Step Payroll Routing: Configuring Your Automated Cash Flow Waterfall
- 8. Building the Waterfall Sequence
- 9. 4. Real-World Blueprint Scenarios
- 10. Blueprint A: The W-2 Professional Aiming for a 25% Savings Rate
- 11. Blueprint B: The Dual-Income “Yours, Mine, and Ours” Couple
- 12. Blueprint C: The Solopreneur or 1099 Contractor
- 13. 5. Pitfalls, Hidden Traps, and Account Maintenance
- 14. The ACH Weekend Float Trap
- 15. Rate-Chasing Fatigue
- 16. Phantom Subscriptions and Zombie Accounts
- 17. The 1099-INT Tax Surprise
- 18. 6. The Wealth Acceleration Layer: Bridging Cash Reserves to Long-Term Investments
- 19. Frequently Asked Questions
- 20. How much should I keep as a checking account buffer?
- 21. Will opening four or five different bank accounts hurt my credit score?
- 22. What should I do if my employer doesn’t support multiple direct deposit splits?
- 23. Are online high-yield savings accounts safe compared to traditional national banks?
- 24. How often should I re-evaluate my automated bank account setup?
Keeping everything in one bucket forces your brain to run complex mental accounting gymnastics every single day. You end up feeling broke when you have money, and you accidentally overspend right before major bills clear.
That frustration led me down an obsessive rabbit hole. I tested multi-account banking setups, broke transfers, paid accidental overdraft fees, and spent years fine-tuning what I now call the automated cash flow architecture. Once you wire your bank accounts together correctly, saving money stops being a daily test of willpower. It turns into an invisible background process that runs on code and bank protocols.
1. The Psychology of Frictionless Saving: Why Traditional Budgeting Fails and Systems Win
Most financial advice tells you to track every cup of coffee in a mobile app or manually log grocery receipts into an Excel sheet. That works for about three weeks. Then life happens—you get sick, work gets crazy, or you forget to log a weekend trip—and the entire tracking habit collapses under its own weight.
This happens because of Parkinson’s Law of Money: your expenses will naturally rise to meet your available balance. If your paycheck lands in a single checking account and sits there looking pretty, your brain treats that total number as “spendable funds.” You buy the nicer sneakers, upgrade your flight seat, and order takeout three nights in a row. By the 25th of the month, the balance has evaporated.
Willpower is a finite biological resource. You burn it making decisions at work, dealing with traffic, and parenting your kids. If your savings strategy depends on you consciously choosing not to spend money sitting right in front of you, you will eventually lose that battle.
The fix is architectural, not psychological. By physically separating your money the moment it arrives, you remove the decision entirely. You don’t need discipline when the cash was moved before your eyes ever registered it as available spend.
💰 More Cheap Living Tips You'll Love
- The Real Cost of Daily Convenience Habits That Steal Thousands Every Year
- Costly Car Ownership Mistakes That Secretly Drain Your Budget Every Month
- The High-Yield Savings Account Strategy That Makes Passive Cash Daily
- Practical Ways to Eat Healthy on a Bare-Bones $50 Weekly Budget
- Hidden Medical Bill Errors You Must Dispute Immediately to Save Big
- Dangerous Lifestyle Creep Signs That Are Quietly Keeping You Broke
2. The 4-Tier Automated Architecture: Organizing Accounts for Maximum Output
To build an automated system that never stalls, you need to segregate your capital based on its job and time horizon. I divide my banking landscape into four distinct tiers:
[PAYROLL / DIRECT DEPOSIT]
            │
            ├──► Tier 1: Everyday Operational Checking (Variable Spend)
            ├──► Tier 2: Fixed Obligations Checking (Mortgage, Utilities, Subs)
            └──► Tier 3: High-Yield Savings Account (Emergency Fund & Sinking Funds)
                                 │
                                 └──► Tier 4: Wealth Engine (Roth IRA, HSA, Taxable Brokerage)
Tier 1: Operational Hub (Everyday Checking)
This is your guilt-free spending container. Groceries, Friday night drinks, gas, haircuts, clothes, and concert tickets live here.
The rule for Tier 1 is simple: if this account balance hits zero, you stop spending on non-essentials until the next paycheck. You never have to worry about bouncing your rent check because your rent money doesn’t live here.
Tier 2: Fixed Obligations (Bills Checking)
This account exists solely to service recurring, non-negotiable overhead.
- Rent or mortgage payments
- Electric, water, and internet bills
- Auto loan notes and insurance policies
- Recurring software subscriptions (Netflix, Spotify, gym memberships)
No debit card should ever touch this account for an in-store swipe. You lock this account away behind online bill pay and auto-debits. Because variable lifestyle spending can’t reach it, you never risk missing an essential payment.
Tier 3: Targeted Liquidity (HYSA Sinking Funds)
Tier 3 handles medium-term cash needs stored in a High-Yield Savings Account (HYSA). Leaving cash in a traditional brick-and-mortar savings account earning 0.01% is financial self-sabotage when modern institutions offer yields north of 4% to 5%.
Verify that any institution you use carries Federal Deposit Insurance Corporation (FDIC) coverage (for banks) or National Credit Union Administration (NCUA) coverage (for credit unions) up to the standard $250,000 legal limit per depositor.
Within this tier, you run separate sub-accounts or “buckets” for:
- Core Emergency Fund: 3 to 6 months of absolute baseline living expenses.
- Sinking Funds: Predictable future expenses that hit irregularly. Think car registration fees, annual Amazon Prime subscriptions, bi-annual dental cleanings, or holiday gifts.
Tier 4: The Wealth Engine (Investment Vehicles)
This tier turns earned income into generational freedom. Money piped here gets locked into long-term compounding assets:
- Roth IRA (post-tax retirement growth)
- Health Savings Account (HSA) (the triple-tax-advantaged unicorn for those with qualifying high-deductible health plans)
- Non-retirement taxable brokerage accounts (using broad-market index funds)
3. Step-by-Step Payroll Routing: Configuring Your Automated Cash Flow Waterfall
Here is where the magic happens. You have two ways to push money through your account structure: Direct Deposit Splits at the employer payroll level, or post-deposit Automated Clearing House (ACH) Transfers.
| Feature | Employer Direct Deposit Split | Post-Deposit ACH Transfer | | :— | :— | :— | | Execution Point | Employer payroll portal (Workday, ADP, Gusto) | Your personal primary bank | | Speed | Instant on payday (funds land simultaneously) | 1 to 3 business days settlement delay | | Failure Risk | Extremely low (runs before you see the cash) | Moderate (can bounce if balances are miscalculated) | | Setup Flexibility | Limited by employer portal options (often max 3-4 splits) | Unlimited custom schedules and dollar amounts |
Whenever possible, configure a Direct Deposit Split inside your employer’s HR software. It prevents the cash from ever touching your everyday checking account.
Building the Waterfall Sequence
Let’s assume your net take-home pay is $4,000 every two weeks. Here is how your Cash Flow Waterfall should drop through your accounts:
- Payday (Day 0): Payroll routes $1,600 directly to Tier 2 (Fixed Bills Checking), $600 to Tier 3 (HYSA Sinking Funds), and the remaining $1,800 to Tier 1 (Everyday Spend Checking).
- Day 2: An automated sweep pulls $300 from Tier 1 into your Tier 4 Wealth Engine (e.g., funding a Roth IRA for routine Dollar-Cost Averaging).
- Throughout the Month: Fixed bills draw autonomously from Tier 2. Everyday life draws from Tier 1.
                  ┌───────────────────────────────┐
                  │ Net Paycheck: $4,000 (Day 0)  │
                  └──────────────┬────────────────┘
                                 │
         ┌───────────────────────┼───────────────────────┐
         ▼                       ▼                       ▼
┌──────────────────┐    ┌──────────────────┐    ┌──────────────────┐
│ Tier 2: Bills    │    │ Tier 3: HYSA     │    │ Tier 1: Spend    │
│ $1,600 (Fixed)   │    │ $600 (Savings)   │    │ $1,800 (Spend)   │
└──────────────────┘    └──────────────────┘    └────────┬─────────┘
                                                         │ (Day 2 Sweep)
                                                         ▼
                                                ┌──────────────────┐
                                                │ Tier 4: Wealth   │
                                                │ $300 (Invest)    │
                                                └──────────────────┘
Expert Insight: The Two-Day ACH Settlement Buffer
Never schedule an automated investment or bill-pay withdrawal on the exact calendar day your paycheck deposits. Payroll processing can shift due to federal bank holidays (like Juneteenth, Memorial Day, or Labor Day). If your company’s payroll drops 12 hours late, your scheduled outgoing ACH transfer will trigger an overdraft fee or bounce entirely. Build a mandatory 48-hour delay into every internal transfer rule.
To protect yourself against edge-case timing errors, establish a permanent Checking Account Buffer. This is a non-negotiable cash cushion (usually $500 to $1,000) that permanently sits in your Tier 2 Bills Checking. You consider that buffer to be your account’s “zero.” If the balance hits $500, the tank is empty.
4. Real-World Blueprint Scenarios
Different careers and relationships require unique tweaks to the plumbing. Here is how to adapt this structure across various life stages.
Blueprint A: The W-2 Professional Aiming for a 25% Savings Rate
- Profile: Single software engineer, salaried, steady bi-weekly pay.
- Execution: Direct deposit routes 25% of net pay straight to an external HYSA at an online bank (like Ally, Marcus, or Capital One 360). 45% routes to a local credit union checking account for rent, utility payments, and insurance. The leftover 30% lands in a user-friendly checking account paired with a debit card (like Schwab or a standard checking account) for daily living.
- Result: They save a quarter of their earnings without looking at a spreadsheet.
Blueprint B: The Dual-Income “Yours, Mine, and Ours” Couple
- Profile: Married couple with shared housing costs but individual discretionary spending preferences.
- Execution:
- Both partners route their calculated share of fixed household expenses (mortgage, groceries, daycare, power bills) via direct deposit into a Joint Tier 2 Checking Account.
- A shared percentage flows to a Joint Tier 3 HYSA for family vacations and home repairs.
- The remainder drops into their Separate Tier 1 Personal Accounts.
- Result: Zero arguments about whether one partner bought an expensive pair of boots or a video game console. As long as the joint bills and shared savings targets are funded at the payroll level, individual checking balances are 100% autonomous and guilt-free.
Blueprint C: The Solopreneur or 1099 Contractor
- Profile: Freelance designer with fluctuating monthly revenue ($4,000 one month, $11,000 the next).
- Execution: Client invoices are paid into a Business Checking account. The freelancer routes 30% immediately to a dedicated Business Tax HYSA.
- The remaining funds sit in an “Income Holding/Buffer Account.” On the 1st and 15th of every month, they pay themselves an identical, steady “salary” transfer into their personal Tier 1 and Tier 2 accounts, regardless of what came in that week.
- Result: Smooths out the feast-or-famine cycle and makes personal wealth automation reliable.
5. Pitfalls, Hidden Traps, and Account Maintenance
Automated systems run beautifully until an edge case jams the gears. Over five years of running this exact layout, I’ve hit almost every snag possible. Here is what to watch out for:
The ACH Weekend Float Trap
ACH transfers do not settle on weekends or Federal Reserve holidays. If you set an auto-transfer for the 15th of the month and the 15th lands on a Saturday, that money might not pull until Monday night, settling on Tuesday or Wednesday. If your bills auto-pay on Tuesday morning, you risk a failed payment if your balances run razor-thin. Maintain that checking account buffer.
Rate-Chasing Fatigue
Don’t jump banks every time an institution launches a promotional APY that is 0.15% higher. The administrative friction of updating direct deposit forms, re-linking ACH connections, and monitoring new logins isn’t worth the $15 annual difference on a $10,000 balance. Pick a reputable, established provider with a great track record and stick with them.
Phantom Subscriptions and Zombie Accounts
Check-splitting makes fixed costs so quiet that you might forget what is draining Tier 2. Run a quarterly audit. Log into your Bills Checking once every three months, review every line item, and cancel services you haven’t touched in 30 days.
The 1099-INT Tax Surprise
Modern High-Yield Savings Accounts generate meaningful interest income. Keep in mind: that interest is taxable as ordinary income at both federal and state levels. If your HYSA yields $1,200 in interest over the year, expect a Form 1099-INT in January. If you don’t withhold accordingly, you will owe a small balance come April.
6. The Wealth Acceleration Layer: Bridging Cash Reserves to Long-Term Investments
Once your emergency fund is fully capitalized inside your HYSA, stop hoarding excess cash. Inflation silently erodes the purchasing power of idle reserves, even inside a high-yield account.
This is where you activate the automated sweep to Tier 4.
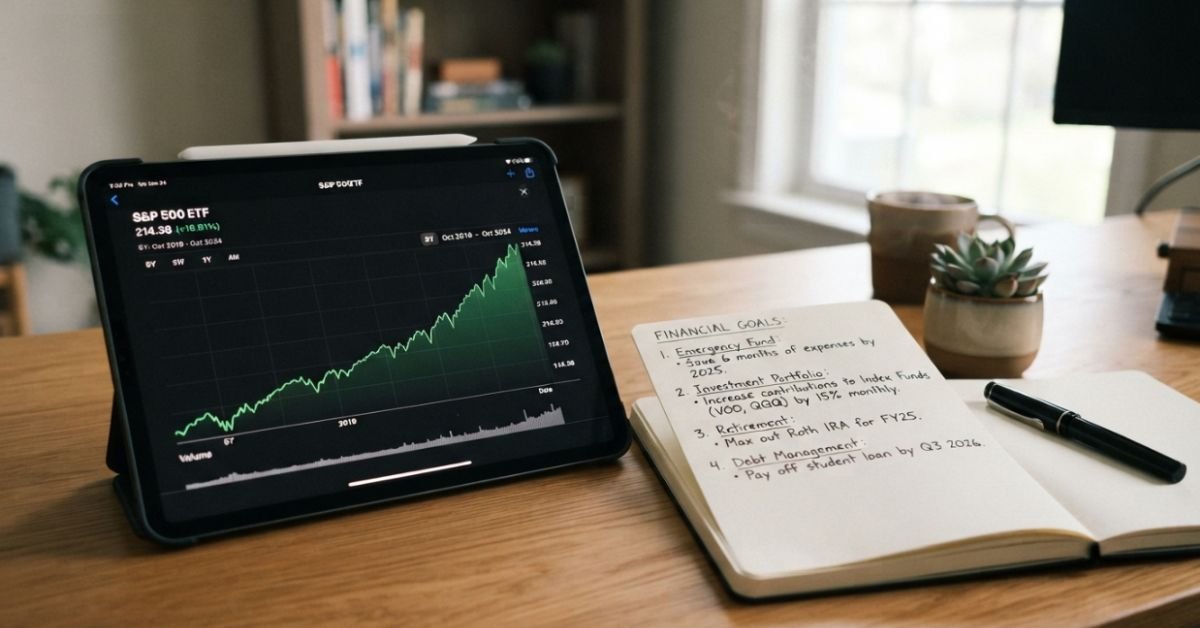
Set a strict “Cap Limit” on your Tier 3 liquid savings. For example, if your 6-month baseline emergency fund plus known sinking funds equals $25,000, your cap is $25,000.
Configure an automated monthly rule: any balance over that threshold gets pushed immediately into your wealth-building engines:
- The First Stop: Maxing out your annual Roth IRA contributions via automated weekly or monthly deposits.
- The Second Stop: Your Health Savings Account (HSA), investing the cash balance into low-cost index funds if your custodian allows it.
- The Final Stop: A plain-vanilla, low-fee taxable brokerage account purchasing broad-market index funds (like total stock market or S&P 500 ETFs).
By implementing this final bridge, you remove the emotional hesitation of “timing the market.” You buy during market peaks, and you buy during terrifying market crashes. That systematic, automated consistency is how ordinary earners assemble serious investment portfolios.
Frequently Asked Questions
How much should I keep as a checking account buffer?
A good rule of thumb is either a flat $1,000 or 25% of your total monthly fixed obligations, whichever is larger. Keep this money permanently parked in your Tier 2 Bills Checking account. Treat this buffer as an absolute zero balance to absorb accidental overlaps in billing cycles or payroll processing holidays without triggering overdraft fees.
Will opening four or five different bank accounts hurt my credit score?
No. Deposit accounts (checking and savings accounts) are not credit products. Opening a checking or savings account usually involves a soft pull on your ChexSystems or Early Warning Services (EWS) report, not a hard inquiry on your credit report from Equifax, Experian, or TransUnion. Your credit score only moves if an account goes negative, stays unpaid, and gets sent to a collections agency.
What should I do if my employer doesn’t support multiple direct deposit splits?
If your employer’s payroll system only allows a single direct deposit destination, route 100% of your paycheck into your Tier 2 Fixed Obligations account. From there, set up automated outgoing ACH transfers from that bank’s online interface to push money out to your Tier 1 Spending checking account, Tier 3 HYSA, and Tier 4 brokerage accounts two business days after payday.
Are online high-yield savings accounts safe compared to traditional national banks?
Yes, as long as they are backed by the FDIC or NCUA. These insurance protections cover your deposits dollar-for-dollar up to $250,000 per depositor, per ownership category, in the unlikely event of an institutional failure. Online banks offer higher yields simply because they don’t have to pay for thousands of physical brick-and-mortar branches, teller staff, and commercial real estate leases.
How often should I re-evaluate my automated bank account setup?
Review your system twice a year or whenever a major life event occurs (such as a job change, a pay raise, a relocation, or a new baby). Check your fixed expenses against your current Tier 2 allocations, confirm your checking buffers are healthy, verify that your sinking fund targets match reality, and increase your automated investment contributions whenever your income grows.