How a Mid-Year Financial Reset Can Completely Transform Your Savings (Step-by-Step Guide).Every January, millions of people scribble ambitious financial resolutions on clean notebooks: “Max out my Roth IRA,” “Save $10,000,” “Pay off the credit cards.”
- 1. 1. The Psychology of the Halfway Mark: Why July Trumps January for Budgeting
- 2. 2. Diagnosing Cash Leaks: Subscription Audits and Discretionary Trimming
- 3. The 6-Month Historical Cull
- 4. Expert Insight: The Ghost Subscription Trap
- 5. 3. Recalibrating Debt Strategy in a High-Interest Environment
- 6. How to Negotiate Rates with US Card Issuers
- 7. 4. Optimizing Savings Architecture with HYSAs and Sinking Funds
- 8. Structuring Your Sinking Funds for Q3 and Q4
- 9. 5. Retirement Contribution Realignment and Tax-Advantaged Growth
- 10. How to Catch Up on 401(k) Contributions Mid-Year
- 11. Don’t Overlook the HSA
- 12. 6. The Mid-Year Financial Checklist 2025: Your Step-by-Step Blueprint
- 13. Step 1: The Cash Flow Audit
- 14. Step 2: Debt & Credit Health
- 15. Step 3: Cash Reserves & High-Yield Upgrades
- 16. Step 4: Investment & Retirement Realignment
- 17. Designing Your Resilient Q3 and Q4 Financial Roadmap
- 18. Frequently Asked Questions
- 19. How do I catch up on my 401(k) if I haven’t contributed all year?
- 20. Is July really better than January for starting a budget?
- 21. How much cash should I keep in an emergency fund right now?
- 22. What’s the fastest way to drop my credit card interest rate?
By March, those resolutions quietly bleed out. By June? Life happened.
Maybe your car’s transmission decided to implode, your spring property tax assessment came back higher than expected, or inflation—measured by a stubborn Consumer Price Index (CPI)—quietly chewed through your grocery allocation.
I’ve spent over a decade working with personal finance tech, coaching clients through messy balance sheets, and managing my own household cash flow. I’ll let you in on an industry secret: January is the absolute worst time to set financial plans. You’re emotionally exhausted from the holidays, guessing at tax outcomes, and running on manufactured enthusiasm.
July, on the other hand, gives you something January never could: hard, indisputable data.
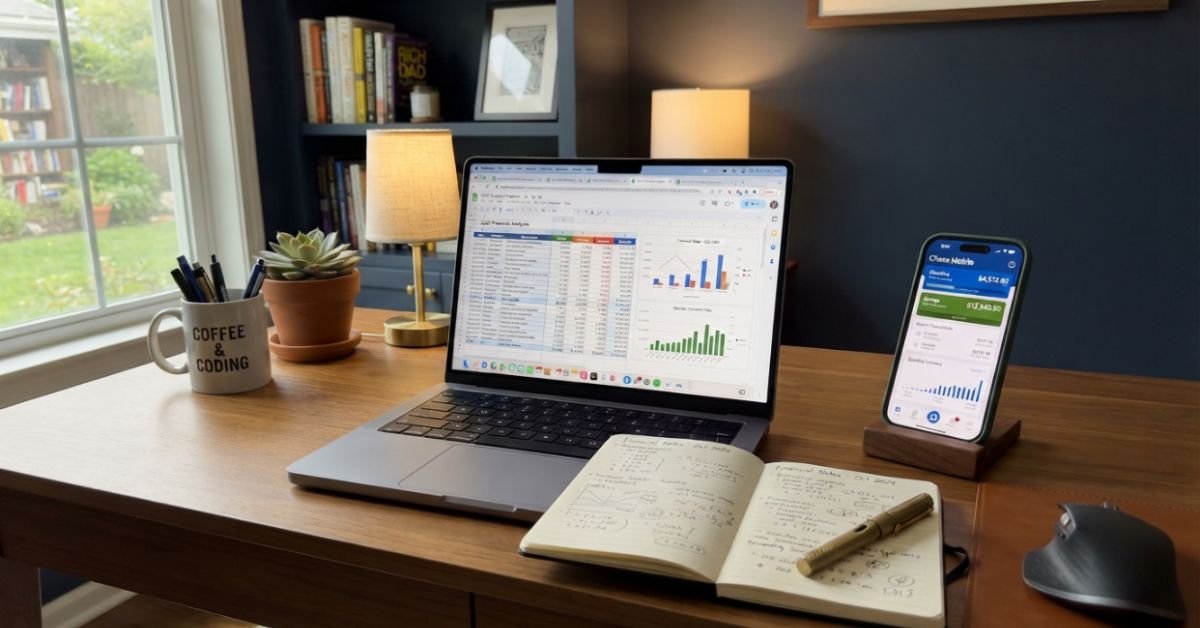
A mid-year financial reset strips away wishful thinking. You have exactly six months of actual bank statements, clear paycheck withholdings, and visible lifestyle trends to examine. If your accounts feel off track, take a breath. You still have six full months to pivot, optimize your cash flow, and finish the year financially bulletproof.
1. The Psychology of the Halfway Mark: Why July Trumps January for Budgeting
Most New Year’s resolutions fail because they rely on motivation rather than behavioral infrastructure. In January, you’re projecting a hypothetical version of yourself. In July, you are confronted with reality.
💰 More Cheap Living Tips You'll Love
- Dangerous Lifestyle Creep Signs That Are Quietly Keeping You Broke
- The High-Yield Savings Account Strategy That Makes Passive Cash Daily
- Costly Car Ownership Mistakes That Secretly Drain Your Budget Every Month
- Practical Ways to Eat Healthy on a Bare-Bones $50 Weekly Budget
- Smart Bank Account Structuring Strategies to Automate Wealth Building
- How to Stop Impulse Buying Forever with the Seven-Day Rule
Think about your last six months. Did you receive a spring tax refund only to watch it vanish into general checking? Did a modest cost-of-living raise get eaten up by silent lifestyle creep?
When I sat down with my clients Marcus and Elena last summer, they were spiraling. They live in suburban Atlanta, earn a combined $145,000, and could not understand why their savings balance had stagnated since February. They assumed they needed a more aggressive side hustle.
The diagnosis wasn’t an income problem; it was resolution fatigue. They had attempted an ultra-restrictive January spending freeze, burned out by Valentine’s Day, and spent the entire spring in a state of financial apathy.
Learning how to reset my finances mid year requires shifting from punishment to pragmatism:
- Acknowledge the sunk cost: What you spent between January and June is gone. Beating yourself up over a pricey April vacation won’t recoup a dime.
- Audit reality, not fantasy: Pull your actual statements from January 1 through June 30. Your debit card doesn’t lie, even when your memory tries to.
- Capitalize on the “Fresh Start Effect”: Psychologists recognize temporal landmarks (birthdays, new months, mid-year points) as natural cognitive resets. July is the ultimate balance beam between past performance and future potential.
2. Diagnosing Cash Leaks: Subscription Audits and Discretionary Trimming
Before you can redirect capital into wealth-building vehicles, you have to plug the hull. Cash leaks rarely look like giant $2,000 splurges; they are usually slow, agonizing drips that disguise themselves as normal operating costs.
If you don’t already have a dedicated tool, open your bank portal or fire up your favorite budgeting app (I alternate between YNAB and Monarch Money depending on whether a client prefers strict allocation or holistic cash-flow tracking).
The 6-Month Historical Cull
Export your checking and credit card transactions from January 1 to the present into a CSV file. Sort by vendor name. You’re hunting for:
- Ghost Subscriptions: Streaming services you haven’t opened in 60 days, annual software auto-renewals (that cloud backup service you forgot you bought), and neglected fitness apps.
- Convenience Fees: App-based grocery delivery upcharges, rideshare surge pricing, and food delivery platform markups.
- Discretionary Creep: Micro-transactions at convenience stores, coffee runs, and online shopping carts checked out past 10 PM.
Expert Insight: The Ghost Subscription Trap
When running a mid-year diagnostic with an engineering client in Texas, we discovered he was paying for two separate Apple iCloud tiers across different family accounts, an obsolete gym membership from an apartment he moved out of in March, and a business SaaS subscription he stopped using in 2023. Total recovered capital: $342 per month. That’s over $4,100 annualized—redirected straight to an investment account with a single afternoon of phone calls and cancellations.
The common pitfall here is swinging the pendulum too far. Don’t cancel your Saturday morning coffee ritual if it brings you genuine sanity. Strip away the spending you don’t even remember doing so you can preserve cash for what you actually value.
3. Recalibrating Debt Strategy in a High-Interest Environment
With Federal Reserve interest rates remaining elevated, holding revolving credit card debt is more punitive than it has been in decades. If you carry a balance on an average rewards card, your APR is likely hovering somewhere between 21% and 29%.
At those rates, traditional minimum payments are quicksand.
Take a hard look at your Debt-to-Income Ratio (DTI) and your Credit Utilization Ratio. If your balances crept up during spring travel or unexpected home repairs, July is the moment to stop the bleeding.
       DEBT REPAYMENT STRATEGIES AT A GLANCE
┌───────────────────┬───────────────────────────────────────────┐
│ Strategy          │ Best Suited For                           │
├───────────────────┼───────────────────────────────────────────┤
│ Debt Avalanche    │ Math-focused optimizers aiming to pay the │
│                   │ absolute lowest total interest (Target    │
│                   │ highest APR first).                       │
├───────────────────┼───────────────────────────────────────────┤
│ Debt Snowball     │ People who need fast psychological wins   │
│                   │ to build momentum (Target lowest balance  │
│                   │ first).                                   │
└───────────────────┴───────────────────────────────────────────┘
How to Negotiate Rates with US Card Issuers
Few cardholders realize that credit card APRs are often negotiable, especially if you have a documented history of on-time payments.
Pick up your phone, dial the number on the back of your card (Chase, Citi, Discover, or Amex), and use this exact script:
“Hi, I’m reviewing my accounts for a mid-year budget rebalance. I’ve been a cardholder with you for [X] years and have consistently paid on time. However, my current APR of 24.99% is uncompetitive compared to balance transfer offers I’m receiving from other institutions. Can you check my account for any available promotional APR reductions or hardship rate programs to lower this interest rate immediately?”
Will it work every time? No. But it works roughly 35% of the time, and dropping an APR by even 4-6 points over the remaining six months of the year can save hundreds of dollars in compounding interest while you aggressively execute an avalanche paydown.
4. Optimizing Savings Architecture with HYSAs and Sinking Funds
Leaving your liquid reserves in a traditional big-bank checking or savings account paying 0.01% APY isn’t just conservative—it’s actively losing purchasing power to inflation.
If you are rebuilding an emergency fund halfway through the year, you need your cash working in an FDIC-insured High-Yield Savings Account (HYSA). Leading institutions currently offer yields between 4.00% and 5.00% APY. On a $15,000 emergency cushion, that is the difference between earning $1.50 a year at a legacy brick-and-mortar bank versus pocketing $600 to $750 in pure, low-risk passive income.
Annual Yield on a $15,000 Emergency Reserve:
Traditional Bank Savings (0.01% APY):  $1.50
High-Yield Savings Account (4.50% APY): $675.00
Structuring Your Sinking Funds for Q3 and Q4
The second half of the calendar year is historically the most expensive for American households. Back-to-school shopping hits in August, followed by Halloween, Thanksgiving travel, and December holidays.
People act surprised by Christmas every single December, scrambling for credit cards and starting the next year deep in debt.
Break this cycle right now. If you’re figuring out how to save money starting in July, the answer is custom sinking funds.
- Calculate the expense: Estimate holiday gifts, travel, and back-to-school supplies. Let’s say it totals $1,800.
- Divide by remaining pay periods: If you get paid bi-weekly, you have approximately 12 to 13 paychecks between July 1 and mid-December.
- Automate the split: Set up an automatic transfer of $140 to $150 per paycheck into a dedicated, labeled sub-account (e.g., “Holiday Travel & Gifts”) inside your HYSA.
By December 15, the money is already there. No interest. No buyer’s remorse. No January debt hangover.
5. Retirement Contribution Realignment and Tax-Advantaged Growth
Your mid-year checkup is your best opportunity to audit retirement vehicles before tax-year deadlines close in. If you wait until November or December to adjust your payroll deductions, you won’t have enough remaining paychecks to make a meaningful dent without suffocating your take-home pay.
┌─────────────────────────────────┬───────────────────────────────┐
│ Account Type                    │ 2025 IRS Annual Limit         │
├─────────────────────────────────┼───────────────────────────────┤
│ 401(k), 403(b), Most 457 Plans  │ $23,500 (Catch-up: $7,500)    │
│ Traditional & Roth IRAs         │ $7,000 (Catch-up: $1,000)     │
│ Health Savings Account (HSA)    │ $4,300 (Self) / $8,550 (Fam)  │
└─────────────────────────────────┴───────────────────────────────┘
How to Catch Up on 401(k) Contributions Mid-Year
If you’re asking how to catch up on 401k contributions mid year, run the simple math today:
- Look at your latest paystub to find your year-to-date (YTD) employee contribution.
- Subtract your YTD contribution from the annual IRS limit (or your personal goal).
- Divide that remaining balance by the number of paychecks left in the calendar year.
- Log into your employer’s benefits portal (NetBenefits, Vanguard, ADP) and adjust your contribution percentage accordingly.
Beware the Match Trap: Check if your employer offers a “true-up” provision for their 401(k) matching contribution. Some employers only match contributions on a per-paycheck basis. If you ramp up contributions too aggressively and hit the IRS limit early (say, in October), you could miss out on company-matching dollars for November and December if no true-up clause exists.
Don’t Overlook the HSA
If you’re enrolled in a qualifying High-Deductible Health Plan (HDHP), your Health Savings Account (HSA) is one of the most potent wealth-building tools in the US tax code. It features a triple tax advantage: contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are completely tax-free. Check your YTD contributions and adjust them so you hit the ceiling by your final December paycheck.
6. The Mid-Year Financial Checklist 2025: Your Step-by-Step Blueprint
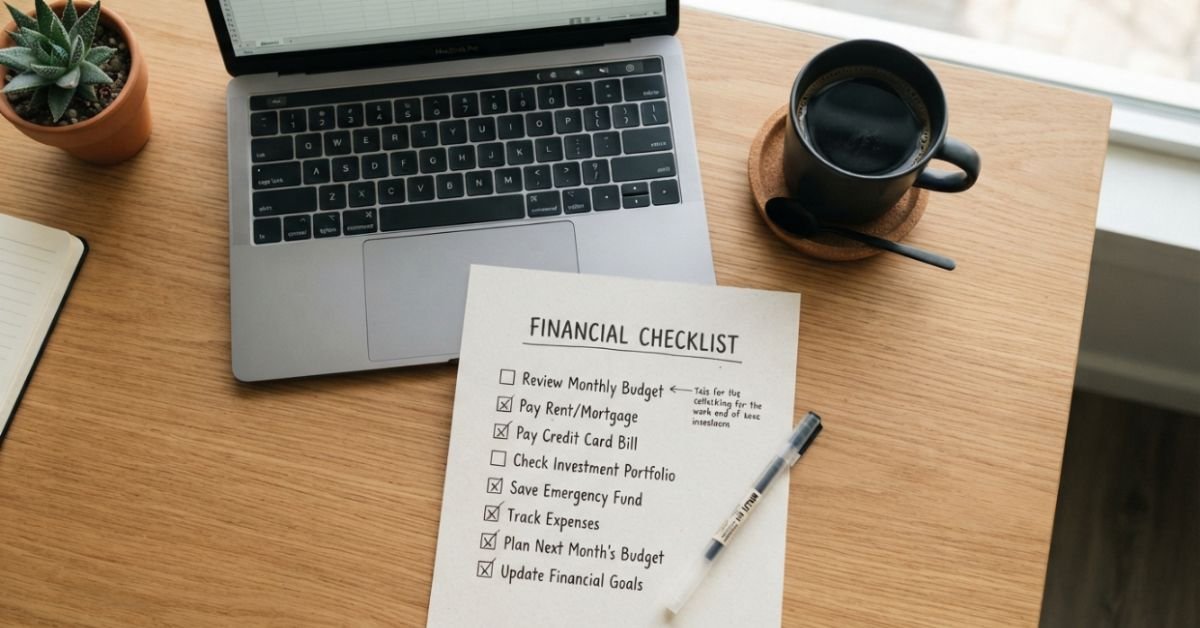
To make this reset practical, run through this tactical mid year financial checklist 2025. You can copy this framework directly into your notes app or build your own half year budget review template.
Step 1: The Cash Flow Audit
- [ ] Pull all bank and credit card statements from January 1 through June 30.
- [ ] Calculate your true monthly burn rate (fixed expenses + average discretionary spend).
- [ ] Cancel at least three recurring services you do not actively use.
- [ ] Update your W-4 withholding status with HR if your family size, homeownership, or income materially changed.
Step 2: Debt & Credit Health
- [ ] Pull your free weekly credit reports via AnnualCreditReport.com to verify there are no reporting errors.
- [ ] Check your aggregate credit utilization ratio (aim to keep it below 10-30%).
- [ ] Rank outstanding consumer debts by APR and implement either the Snowball or Avalanche method.
- [ ] Call issuers to request an interest rate reduction or evaluate a fee-conscious 0% APR balance transfer.
Step 3: Cash Reserves & High-Yield Upgrades
- [ ] Ensure your liquid emergency fund sits inside an FDIC-insured HYSA paying a competitive market rate.
- [ ] Target 3 to 6 months of true living expenses based on current (not theoretical) monthly burn.
- [ ] Establish sinking funds for Q3/Q4 obligations (back-to-school, car maintenance, holidays).
Step 4: Investment & Retirement Realignment
- [ ] Verify you are capturing 100% of your employer’s 401(k) match.
- [ ] Adjust payroll percentages to balance remaining annual limits across 401(k), IRA, and HSA vehicles.
- [ ] Rebalance your investment portfolio if spring market volatility drifted your asset allocation off target.
Designing Your Resilient Q3 and Q4 Financial Roadmap
A mid-year reset isn’t an afternoon chore that you check off and forget. It is an operational upgrade to how you run your money.
Implement a 15-minute weekly micro-budgeting system. Set a recurring calendar invite every Sunday evening. Don’t build a complex 40-tab model. Just answer three basic questions:
- What transactions cleared this past week that weren’t planned?
- What unusual expenses are hitting over the next seven days?
- Are my automated transfers to my HYSA and brokerage still executing on time?
When life throws an unexpected summer car repair or a surprise medical bill your way, you don’t have to surrender your progress. Adjust your timeline, lean on your sinking funds or emergency cushion, and keep your core habits intact.
You don’t need a new calendar year to take command of your balance sheet. The best time to fix your money was six months ago; the second best time is today.
Frequently Asked Questions
How do I catch up on my 401(k) if I haven’t contributed all year?
First, verify how many pay periods remain before December 31. Divide the remaining IRS annual maximum ($23,500 for 2025, or $31,000 if age 50+) by the remaining paychecks. Log into your HR benefits portal to increase your contribution percentage. Make sure the higher deduction leaves you enough net pay to cover fixed household expenses, and confirm with payroll that your employer’s match won’t be disrupted by front-loading your contributions.
Is July really better than January for starting a budget?
Yes. January budgets rely on optimistic projections, while July budgets run on six months of actual transaction history. Mid-year budgeting accounts for your true living costs, real-world inflation impacts, and recent tax adjustments. This makes your financial targets much more sustainable.
How much cash should I keep in an emergency fund right now?
Aim for three to six months’ worth of basic living expenses—housing, utilities, food, debt minimums, and insurance. If you are a dual-income household with stable W-2 employment, three to four months may suffice. If you are self-employed, rely on commissions, or work in a volatile industry, lean toward six to nine months of liquid reserves housed safely in an FDIC-insured High-Yield Savings Account.
What’s the fastest way to drop my credit card interest rate?
Call your card issuer’s customer service line directly. Point out your tenure, your on-time payment track record, and reference competitive balance transfer promotions you’ve received in the mail. Politely ask for a permanent APR reduction or placement into a temporary promotional rate program. If they decline, consider transferring the balance to an external card offering a 0% introductory APR for 12 to 21 months, making sure to calculate the standard 3% to 5% balance transfer fee beforehand.